

How to Check Treasury FRN Interest: From Bill Auction Rates to Your Coupon
 zhan chen
A Treasury FRN coupon is a sum of daily accruals, not the latest bill rate multiplied by a quarter. A $100,000 example separates rate conversion, reset timing, the payment lockout and interest paid when buying between coupon dates.
The latest 13-week Treasury bill auction rate does not, on its own, tell you what a Treasury floating-rate note will pay this quarter. There are two separate calculations: convert the bill's discount-rate quote into the FRN's index rate, then apply the rate belonging to each day of the interest period. Looking up the final rate and multiplying it by three months can get both steps wrong.
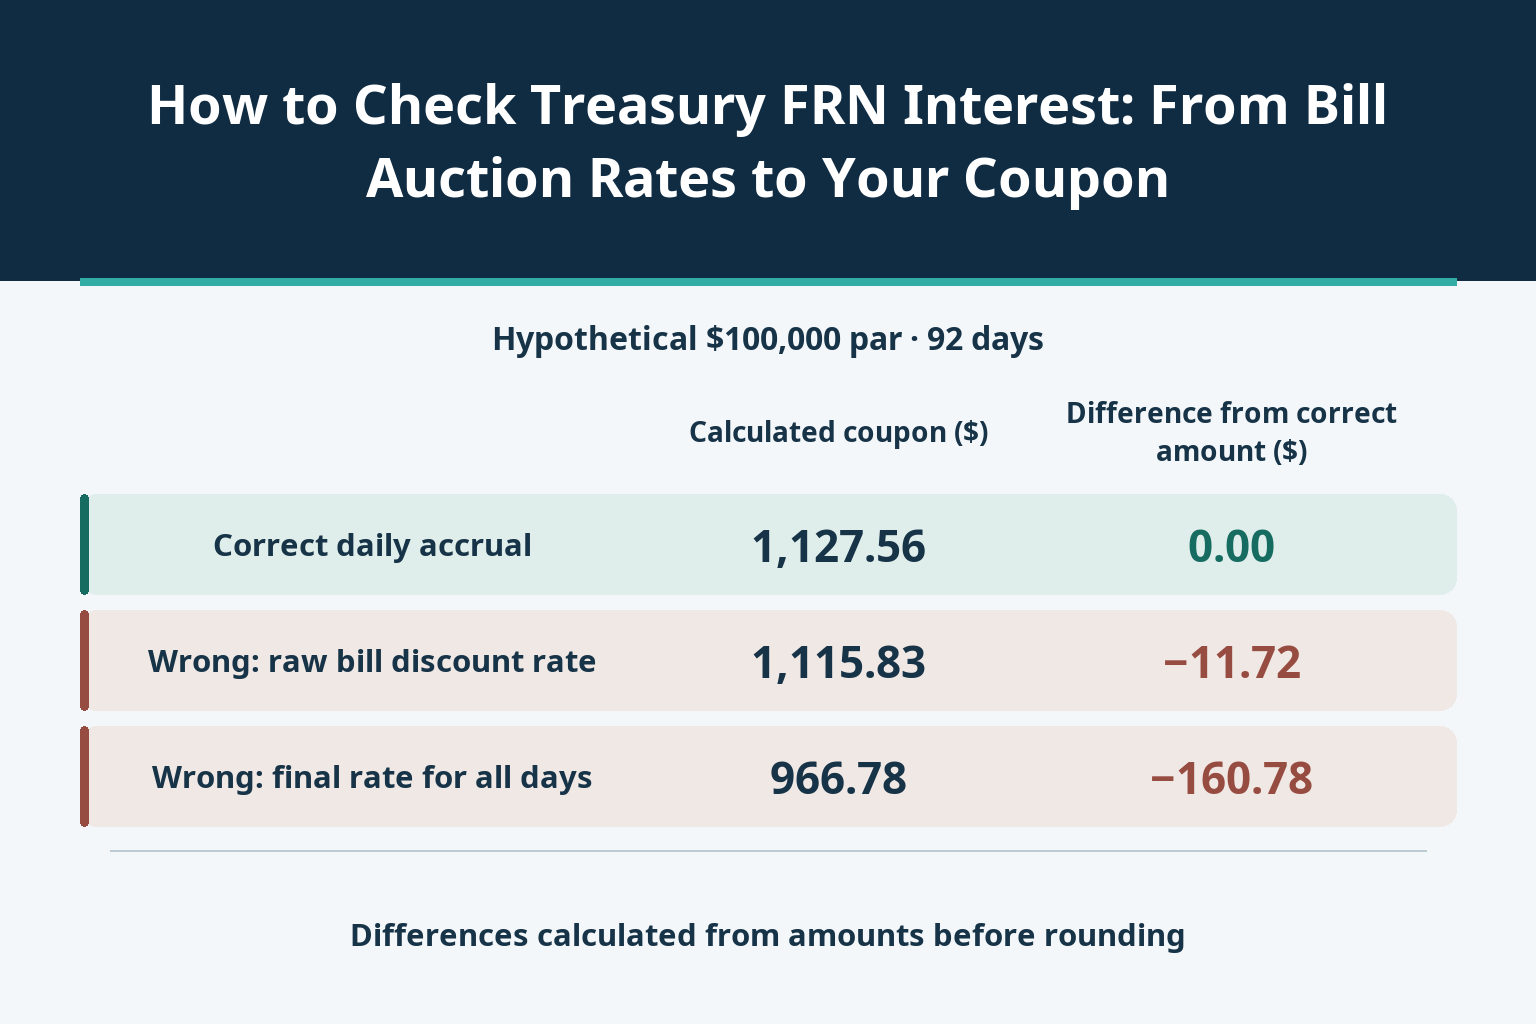
For the hypothetical $100,000 position below, the correct 92-day coupon is $1,127.56. Using unconverted bill discount rates produces $1,115.83. Applying the final coupon rate to the entire period produces only $966.78. Neither discrepancy is evidence of a missing payment: each comes from a specific mistake in the interest ledger.
Separate the bill rate, the FRN index and the fixed spread
This discussion concerns the U.S. Treasury FRN indexed to 13-week bill auctions, not a corporate note tied to an overnight benchmark. Treasury FRNs mature in two years and pay quarterly. Weekly bill auctions usually provide the new reference information, but interest is assigned to calendar days. Quarterly payment does not mean the rate is fixed for three months.
The auction's High Rate is a discount rate: the bill's discount is measured against its redemption value. The FRN index converts that quotation into a simple money-market yield on an actual/360 basis. A fixed spread, set when the FRN is first auctioned, is then added. The spread is not reset every time a new bill auction takes place.
These distinctions matter when reading a screen. A bill High Rate, a bill Investment Rate and an FRN's current interest rate are not three interchangeable labels for the same number. The bill Investment Rate uses a different annualization convention. Equally, a reopening's discount margin is a pricing input, not permission to overwrite the existing note's fixed spread.
Why a 4.500% discount rate becomes a 4.551776457% index
Let d be the bill's annual discount rate expressed as a decimal, and n its actual number of days to maturity. Its price per $100 is P = 100 × (1 − d × n / 360). Measuring the discount against that purchase price, rather than $100, gives the actual/360 simple yield:
r = (100 − P) / P × 360 / n = d / (1 − d × n / 360).
Assume n = 91 and d = 0.045. The bill price is 98.862500, and the converted index is 4.551776457% after rounding the percentage to nine decimal places. Add a hypothetical fixed spread of 0.150%, or 15 basis points, and the FRN accrues at 4.701776457% a year. These are invented inputs for reconciliation, not reported auction results.
| Rate case | Bill High Rate (%) | Bill price per $100 | FRN index (%) | Index + spread (%) | Daily interest ($) |
|---|---|---|---|---|---|
| A: first rate block | 4.500 | 98.862500 | 4.551776457 | 4.701776457 | 13.060490 |
| B: second rate block | 3.600 | 99.090000 | 3.633060854 | 3.783060854 | 10.508502 |
| C: lockout test only | 5.400 | 98.635000 | 5.474730065 | 5.624730065 | 15.624250 |
Row C is reserved for a separate lockout test below; it is not a third rate used in the main coupon. All three bill prices in this example terminate within six decimal places, avoiding an intermediate price-rounding complication. For an actual holding, use the published index and the bill's actual term: “13 weeks” is not a reason to hard-code 91 for every auction.
Keep percentage units explicit. An index displayed as 4.551776457% enters the dollar formula as 0.04551776457. Rounding a decimal rate to nine places is not the same operation as rounding a percentage to nine places. Small unit mistakes repeated across a large position can obscure a genuine timing discrepancy.
Build the 92-day coupon without compounding it
Assume a full interest period containing 92 calendar days and constant par of $100,000. Its applicable-rate ledger assigns A to the first 63 days and B to the final 29. These are assumed stretches of unchanged effective rates; they do not imply that only two bill auctions occurred. Successive weekly auctions can produce the same High Rate.
For each day, interest equals par × max(index + spread, 0) / 360. Add those dollar accruals. Do not increase tomorrow's interest-bearing principal by today's accrued amount. This is daily accumulation, not daily compounding. Include the period's first accrual day and exclude its next interest-payment or maturity date; weekends inside the period still count.
| Accrual block | Calendar days | Applicable annual rate (%) | Interest ($) |
|---|---|---|---|
| Days 1–63 | 63 | 4.701776457 | 822.810880 |
| Days 64–92 | 29 | 3.783060854 | 304.746569 |
| Full period | 92 | — | 1,127.557449 |
The first block contributes $822.810879975 and the second $304.746568794, giving $1,127.557448769 before display rounding. Multiplying the last annual rate, 3.783060854%, by $100,000 × 92/360 instead gives $966.782218244. That erases the earlier, higher-rate days and understates the result by about $160.78.
A different shortcut preserves the 63/29 split but adds the spread directly to the unconverted bill High Rates. It gives $1,115.833333333, about $11.72 too little. The first error assigns the wrong rate to time; the second uses the wrong yield denominator. Fixing one does not fix the other. Dollar amounts shown to cents here are explanatory displays; a statement reconciliation must also respect the paying agent's actual rounding sequence.
The payment lockout can postpone a seemingly obvious reset
Under Treasury's offering rules, the normal rate change follows the bill auction on the next calendar day. A two-business-day lockout before Treasury's issue settlement, including a reopening, or an interest payment creates an exception: a bill auction within that window is excluded from the calculation of that issuance settlement amount or coupon. This is not a new lockout created by every secondary-market purchase. Check the applicable index for the particular CUSIP rather than assuming every newly announced rate immediately enters every note's payment.
Take a separate timing test. Suppose auction C occurs inside the coupon's lockout and, without that restriction, its rate would affect exactly the final accrual day. That day still uses B for this payment. Replacing it prematurely with C adds $15.624250181 − $10.508502372, about $5.12, producing an incorrect $1,132.67 coupon.
The difference is for one explicitly assumed accrual day, not a universal two-day adjustment. Two business days are not always two calendar days, and auction schedules, holidays and the payment calendar matter. The deferred change must be applied according to the published daily record after the lockout; it does not rewrite interest already assigned to earlier days. No assumed calendar date in this model replaces that check.
A buyer receiving the whole coupon has not earned it all
Now suppose the investor buys at the start of day 64. The preceding 63 days' accrued interest is $822.81. Paying that amount at settlement and later receiving the full $1,127.56 coupon leaves approximately $304.75 attributable to the buyer's 29 days, before costs and taxes. The full coupon is a cash receipt; it is not all income newly earned since purchase.
Add an independent assumption that the clean price is 100.20 per $100 par. The price component is $100,200, and the interest component is about $822.81, so the cash settlement is $101,022.81. The $200 premium and the accrued interest have different meanings. The former is part of the price paid for the security; the latter compensates for interest already accumulated before the buyer's settlement.
Neither $1,127.56 divided by par nor by that cash settlement is automatically an annual investment return. A holding-period calculation also needs the eventual sale or redemption proceeds, other cash payments, costs and the actual period held. Treasury's reopening guidance makes the same operational distinction: an unchanged maturity and spread do not require an unchanged price. The separate explanation of why floating-rate bonds can fall despite coupon resets addresses that pricing risk.
Where the simple ledger needs another check
The zero floor applies to the daily sum of index and spread. For a different hypothetical note, an index of 0.100% with a fixed spread of −0.200% gives zero daily interest, not a negative amount to offset another day's positive accrual. That is a separate contract example, not a change to the main note's +0.150% spread.
A floor on interest is not a floor on the purchase or resale price. Nor should today's index be projected through every unknown future day and presented as an already earned coupon. A partial-period ledger can contain verified past accruals and a forecast of remaining accruals, but the two must remain identifiable. Changing a future-rate assumption changes the forecast, not the past ledger.
Finally, do not transfer this method unchanged to a corporate FRN, a fund distribution or a product using compounded overnight rates. Different observation windows, principal changes and payment conventions can change the calculation. Start with the actual instrument, not merely the words “floating rate.”
Five checks before treating a coupon difference as an error
- Identify the CUSIP, par amount, fixed spread, accrual boundaries and payment date. Keep the bill's maturity days separate from the FRN's coupon-period days.
- Obtain that note's daily index record and the relevant bill auction inputs. Distinguish the discount High Rate, converted index and index-plus-spread interest rate.
- Assign the applicable rate to every calendar day, checking lockout dates and any changes in the position. Sum daily interest without compounding it.
- Reconcile the settlement's clean-price component and accrued-interest component separately, then distinguish the full coupon from income attributable to the holding period.
- Compare unrounded intermediate amounts before investigating final-cent differences. Keep confirmed accruals apart from forecasts, and verify the actual payment record.
The useful question is not whether the latest rate looks plausible. It is whether the correct rate, in the correct units, has been assigned to the correct days and to the correct owner's period. Once those three checks are explicit, a Treasury FRN coupon becomes a reproducible cash-flow calculation.


