

TIPS Deflation Floor: Why Buying at 98 Can Still Lose Money at Maturity
 zhan chen
The TIPS maturity floor protects original principal, not a secondary-market buyer’s cost. A final-coupon-period example separates the floor trigger from the buyer’s cash break-even point, accounting for the index-adjusted purchase price and final coupon.
The maturity floor on a Treasury Inflation-Protected Security protects its original principal, not the amount its latest owner paid. Those numbers can be far apart. A TIPS quoted below 100 can still cost more than its original face value once the existing inflation adjustment is included.
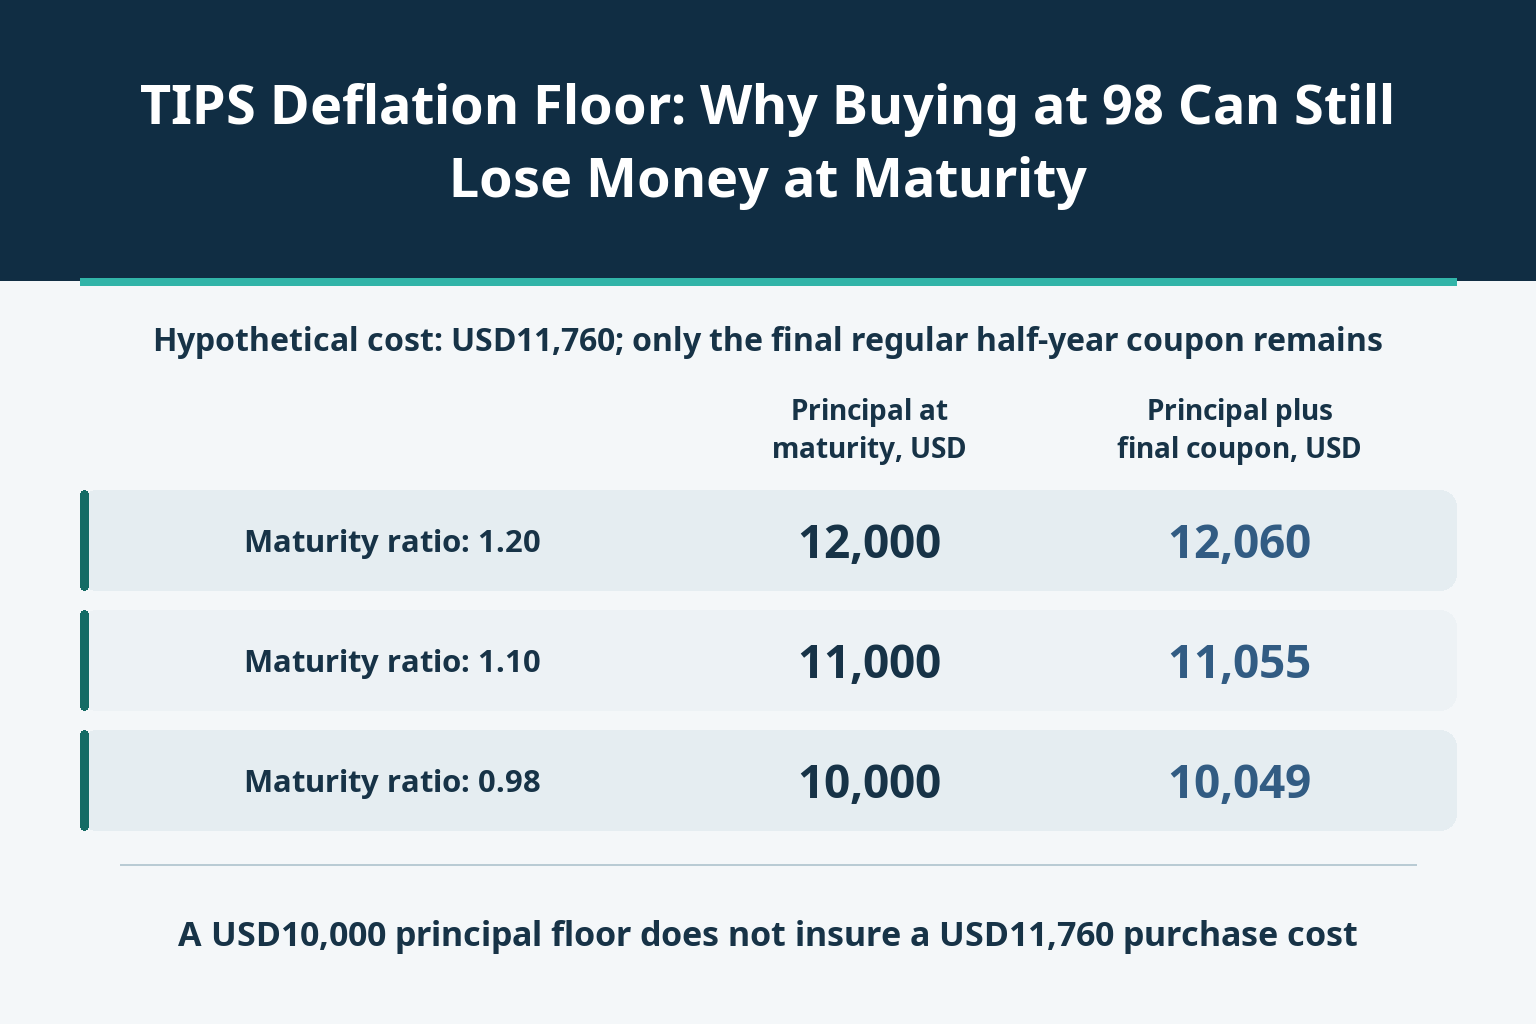
In the hypothetical example below, a quote of 98 produces a cash purchase cost of USD11,760 for USD10,000 original principal. In a severe deflation scenario, the floor works exactly as intended: principal is restored to USD10,000. Yet the final principal and coupon total only USD10,049, leaving a USD1,711 nominal loss for this buyer.
A quote of 98 is not the same as paying USD9,800
Take an existing TIPS with USD10,000 original principal and a fixed annual coupon rate of 1%. It has exactly one regular semiannual coupon period left before maturity. This is not a newly issued six-month TIPS. Assume purchase settlement occurs after the penultimate coupon has been paid, the buyer has no entitlement to that coupon and accrued interest is zero.
The purchase-date index ratio is 1.20. The unadjusted clean quote is USD98 per USD100 of original principal. The cash cost is therefore 10,000 × 1.20 × 98/100 = USD11,760. The adjustment is essential: treating the quote as a USD9,800 invoice omits the indexation embedded in the transaction.
The buyer is paying 98% of USD12,000 inflation-adjusted principal, not 98% of the eventual USD10,000 floor. The accumulated adjustment is not a free bonus, and purchasing it does not lock it permanently into the principal protected at maturity. The original reference base does not reset when the bond changes hands.
Write down the final principal and coupon separately
Let N = USD10,000 and let R be the maturity index ratio, assumed positive. Principal paid at maturity is D = N × max(R, 1). The final regular half-year coupon is C = N × R × 1%/2 = 50R dollars.
Only the first expression contains the principal floor. Replacing the coupon with 50 × max(R, 1) would incorrectly extend that protection to interest. A fixed coupon rate does not mean a fixed coupon amount: the amount depends on the applicable adjusted principal.
Total final cash is D + C. Subtract the USD11,760 purchase cost for nominal profit or loss, or divide total cash by that cost and subtract one for the simple holding-period return. There is only one remaining coupon and no intervening cash flow. The model excludes taxes, fees, financing and reinvestment. The reported returns are unannualized nominal holding-period returns, not real yields or measures of an individual's purchasing power.
The floor can pay out while the buyer still loses
The three rows are independent hypothetical endings, not a forecast or a sequence of observed inflation readings. The same bond, purchase ratio and purchase quote apply in each case.
| Maturity index ratio | Reference-ratio change since purchase, % | Principal at maturity, USD | Final coupon, USD | Total final cash, USD | Nominal profit or loss, USD | Nominal holding-period return, % |
|---|---|---|---|---|---|---|
| 1.20 | 0.000000 | 12,000.00 | 60.00 | 12,060.00 | +300.00 | +2.551020 |
| 1.10 | −8.333333 | 11,000.00 | 55.00 | 11,055.00 | −705.00 | −5.994898 |
| 0.98 | −18.333333 | 10,000.00 | 49.00 | 10,049.00 | −1,711.00 | −14.549320 |
With R = 1.20, principal is USD12,000 and the last coupon is USD60. Final cash of USD12,060 exceeds cost by USD300, a 2.551020% nominal holding-period return. At R = 1.10, principal falls to USD11,000 and the coupon to USD55. The resulting USD11,055 is USD705 below cost, even though the maturity ratio remains above one and the floor provides no top-up.
At R = 0.98, unfloored principal would be USD9,800. The floor adds USD200, taking principal to USD10,000. The coupon is still USD49, not USD50. Total cash is USD10,049, and the USD1,711 loss corresponds to a −14.549320% nominal holding-period return. The protection has not failed; the protected amount is smaller than this buyer's cost.
A ratio of 0.98 also does not mean 2% deflation during this buyer's holding period. The reference ratio fell from 1.20 to 0.98, a decline of 18.333333%. TIPS reference indexing uses a lag: that ratio change is not automatically the change between same-date headline CPI releases or in the investor's personal consumption basket.
The principal floor and the cash break-even point are different thresholds
The floor adds principal only when R is below one; at exactly one, adjusted and original principal are equal. Starting from 1.20, the reference ratio must fall by more than one-sixth, or about 16.666667%, before a positive floor top-up appears. There is no new floor at 1.20 simply because that was the buyer's entry ratio.
Recovering the purchase cost requires a different calculation. For R at or above one, total final cash is 10,050R. Setting that equal to USD11,760 gives a continuous-model break-even ratio of 11,760/10,050 = 1.170149253731… . Relative to the entry ratio, this is a decline of about 2.487562%. The buyer can therefore move into a nominal loss well before the principal floor starts adding anything.
Below one, final cash is 10,000 + 50R, less than USD10,050 and nowhere near the USD11,760 cost. Principal has stopped falling, but the last coupon still changes with R. The floor changes the shape of the maturity cash flow; it does not turn the buyer's total return into a guaranteed non-negative number.
The change in sensitivity is measurable. A 0.01 increase in R adds USD100.50 to final cash when both ratios are at or above one, but only USD0.50 when both are below one. The latter change comes entirely from the final coupon. This comparison describes terminal cash flows, not the floor's market value before maturity.
The long decimal is a mathematical threshold, not an official index ratio quoted to unlimited precision. Actual ratios are expressed to five decimal places, with cash rounding checked separately. Adjacent ratios 1.17014 and 1.17015 give model cash before amount rounding of USD11,759.907 and USD11,760.0075. They straddle break-even. Actual principal and coupon payments must be reconciled to their applicable rounding, not assumed to hit USD11,760 exactly.
The same inflation ending can reward one entry price and penalize another
Keep the purchase ratio, remaining term and coupon unchanged, and fix the final ratio at 1.10. Change only the unadjusted clean purchase quote. These are separate sensitivity cases for the same hypothetical bond, not simultaneously executable market offers.
| Unadjusted clean quote, USD per 100 par | Purchase cost, USD | Final cash if ratio is 1.10, USD | Nominal profit or loss, USD | Continuous-model cash break-even ratio |
|---|---|---|---|---|
| 90.00 | 10,800.00 | 11,055.00 | +255.00 | 1.07462687 |
| 98.00 | 11,760.00 | 11,055.00 | −705.00 | 1.17014925 |
| 102.00 | 12,240.00 | 11,055.00 | −1,185.00 | 1.21791045 |
At 90, cash cost is USD10,800, so the common USD11,055 final payment produces a USD255 gain. At 98 the buyer loses USD705; at 102, the USD12,240 cost produces a USD1,185 loss. The principal contract and final reference-index outcome have not changed. What changed was the price paid for those cash flows.
Each entry price also has a different continuous cash break-even ratio. The table does not derive real yields from the quotes, and its maturity top-up is not a valuation of the embedded floor today. Market pricing contains information that three hypothetical terminal cash rows cannot supply.
What changes if the investor sells early or buys a fund
Before maturity, sale proceeds depend on the transaction price, applicable index ratio, accrued interest and costs. The maturity floor is not a daily market-price guarantee at original principal. A TIPS fund share is also not an individual Treasury promising to repay that shareholder's own purchase cost on a chosen date.
More than one remaining coupon requires more than one cash-flow line. Each coupon uses its applicable reference ratio and arrives on its own date. Adding earlier payments to a maturity total requires an explicit treatment of reinvestment or a consistent valuation date. The single-period construction here deliberately avoids assuming either.
The distinction is also separate from the inflation compensation implied by Treasury yield spreads. That market measure does not specify this investor's invoice or restore the amount paid above original principal. A coupon rate, a real-yield quotation and a nominal holding-period return are not interchangeable measures. Principal protection alone does not establish a non-negative real yield or preserve a personal cost of living.
Five checks before treating the floor as protection for a purchase
- Identify the security, original principal and reference-index base. Obtain the ratio for the actual settlement date rather than substitute a recent inflation headline.
- Check whether the displayed price is unadjusted or already indexed. Reconcile the cash invoice, accrued interest and costs without applying the index ratio twice.
- Map the remaining coupon dates and entitlements. Use the applicable ratio for each coupon; do not extend the principal floor to interest.
- Calculate the floor-trigger threshold and the buyer's cash break-even threshold separately. Respect official ratio precision and payment rounding.
- Distinguish holding the individual bond to maturity from selling it or owning fund shares. Keep nominal cash returns separate from real yields and purchasing-power claims.
The useful question is not merely whether TIPS have a deflation floor. It is what principal that floor protects, how much the buyer actually pays and which cash flows remain. Once those are reconciled, “below par” and “protected principal” no longer conceal the possibility of a loss at maturity.


