
How to Draw Support and Resistance Zones and Spot False Breakouts
 zhan chen
Learn to draw support and resistance zones, use ATR and bar closes to confirm breakouts, assess retests, volume and open interest, and identify false breakouts.
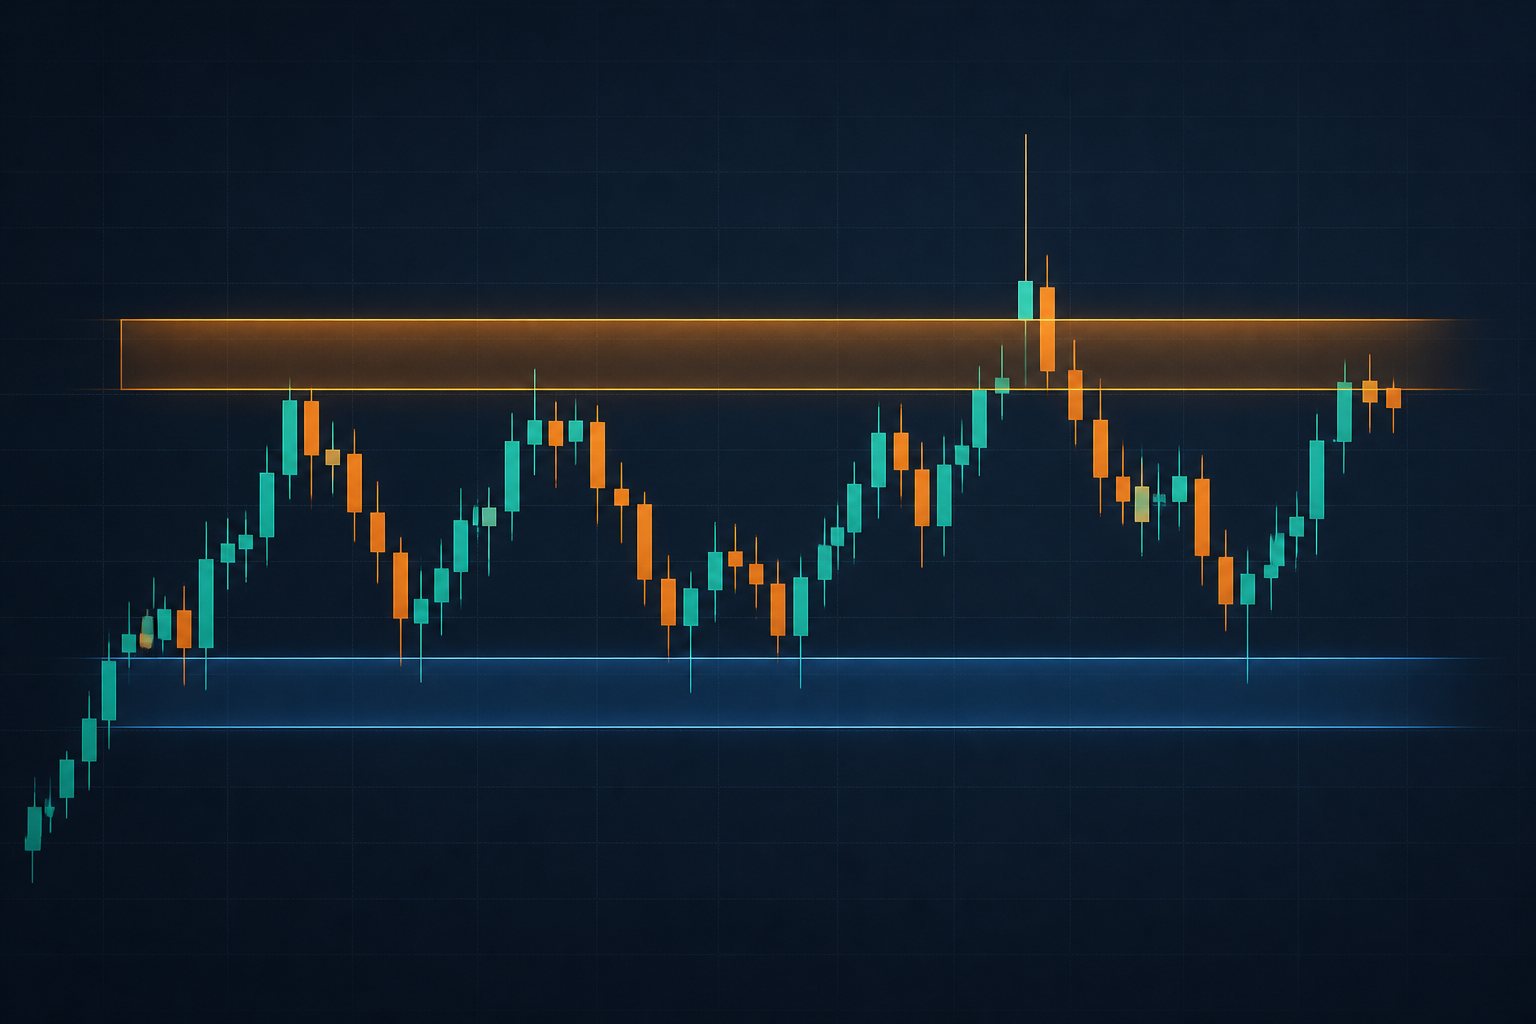
Support and resistance create a seductive illusion of precision. Draw a horizontal line carefully enough, the story goes, and price should obey it. Markets are less tidy. Change the quote feed, trading session, equity-adjustment method or futures contract and the wick may move slightly. Even on identical data, orders do not accumulate at one perfect decimal. A brief excursion beyond a level may reflect spread expansion, thin liquidity or price discovery; it may also be the first sign that the market is relocating its accepted range.
This is Part 3 of the Financial Chart Basics series. The previous practical guide to moving averages placed crossovers inside trend, location and volatility. This instalment tackles the structural question underneath them: how to draw support and resistance as zones, when a boundary crossing becomes acceptance outside the old range, what must happen before resistance can act as support, and how to define a false breakout before seeing the outcome.
Support and resistance are zones, not orders waiting on a line
Support is an area where a decline previously met enough demand, two-way trade or short covering to pause or reverse. Resistance is an area where an advance previously met enough supply, profit-taking or opposing interest to stall. These are descriptions of recorded behaviour, not proof that the same orders remain in place today. A historical high-volume area is not a live order book: the former reflects completed transactions, while the latter displays currently visible orders that can be amended or cancelled.
A useful zone has three layers. Its core is the band containing repeated closes, opens or sustained trade. Its outer boundary is set by representative wick extremes, gap edges or points of rapid rejection. Its volatility allowance absorbs normal feed, session and timeframe noise. A centre line can help the eye, but confirmation and invalidation should refer to the whole area.
Precision is not the same as evidence. Missing a line by one tick does not prove that support worked perfectly; trading one tick through it does not prove that the level failed. If the conclusion depends entirely on the last decimal, the analysis is measuring chart resolution rather than market structure.
Build a zone from closes, wicks and repeated trading activity
Start with confirmed swing highs and lows, the edges of a sustained range or a meaningful gap. Then separate three kinds of evidence. A cluster of closes suggests that the market previously spent time accepting prices there and is a sensible basis for the core. Wicks show where price travelled but failed to remain and are more useful for the outer rejection boundary. Heavy historical activity shows participation, but it may create either a future reference point or another area of two-way congestion.
A reproducible process is more valuable than the prettiest line:
- Move one timeframe higher and mark only completed swings and established ranges. Do not let an unfinished bar define the zone.
- Use clusters of opens, closes and overlapping bodies for the core rather than allowing one exceptional wick to dominate it.
- Use representative wicks, gap edges and rapid rejection points for the outer boundary. Record whether a data release, earnings announcement or liquidity disruption produced them.
- Treat several adjacent bars probing the same area as one test. Counting every bar separately exaggerates the evidence.
- Merge heavily overlapping zones. If horizontal bands cover the entire chart, the selection rule no longer discriminates between useful and ordinary prices.
Nor is “more tests mean a stronger level” a law. Reactions that repeatedly travel a meaningful distance away can strengthen the case that participants recognise an area. Rebounds that become progressively shorter while closes press against the boundary may instead show that available demand or supply is being absorbed. The number of tests matters only when read alongside reaction distance, speed, time spent at the boundary and the structure that follows.
Scale zone width and breakout distance with ATR
A ten-point tolerance cannot carry the same meaning in EUR/USD, gold, an individual share and an equity-index future. Average True Range provides a common volatility language. The single-period true range is:
TR_t = max(H_t - L_t, |H_t - C_(t-1)|, |L_t - C_(t-1)|)
Smoothing TR over the chosen window gives ATR. If P₀ is the centre of a prospective level, a volatility-adjusted research zone can be expressed as:
Zone = [P₀ - q × ATR_n, P₀ + q × ATR_n]
When the area already has a lower boundary D and an upper boundary U, the same principle can add an allowance to either side. The normalised strength of an upward close beyond the zone is:
B_t(up) = (C_t - U) / ATR_t
This distinguishes a close that barely exceeds normal quote noise from one that has travelled materially beyond the old area. It does not create a universal threshold. The choice of q, ATR window and confirmation horizon depends on the instrument, timeframe, session, gap behaviour and trading costs. Calling every move above 0.5 ATR a genuine breakout merely replaces subjective drawing with an untested parameter. Thresholds require out-of-sample and cost-sensitive validation.
A boundary crossing is not acceptance: follow the evidence chain
An intraday high above resistance is a breakout candidate, not a completed verdict. Evidence normally progresses through five states: approach, intrabar test, close beyond the boundary, acceptance outside the area, then continuation or retest. An upside case becomes more credible when the body closes above the zone, the close has a meaningful ATR-scaled margin, it sits near the bar high, later bars mostly remain outside, a pullback does not immediately re-enter the former range, and spreads and liquidity make the move tradable rather than theoretical.
Close Location Value can add one narrowly defined observation:
CLV = [(Close - Low) - (High - Close)] / (High - Low)
CLV approaches 1 when the close is near the high, -1 when it is near the low and 0 around the middle of the range. It is undefined when H equals L. The measure describes the location of one close; it does not prove that buyers or sellers must control the next bar.
Rejection can appear as a wick through the boundary followed by a close back inside, one close outside followed by rapid re-entry, an inability to extend the distance, or the failure of the swing created by a retest. A long upper wick is rejection evidence, not an automatic false breakout. One body close beyond the zone is stronger evidence than a wick, but it still cannot guarantee continuation.
A false breakout therefore needs an ex-ante definition: price crosses a pre-defined boundary, returns to the old area within a specified decision horizon, and triggers a structural invalidation condition. Labelling every breakout that eventually stops trending as “false” is hindsight, not analysis.
When does old resistance really become new support?
Role reversal is not activated by drawing an arrow from “resistance” to “support”. At least three events are required: price first gains acceptance above the former resistance zone; a pullback then reaches or approaches that area; and completed bars reclaim the upper side before price clears the small swing high created by the response. The logic is reversed after a downside break.
A plan can specify confirmation before the test arrives. For example: the breakout bar closes above U; the retest low enters the ATR allowance; most closes do not persist below the lower edge; and price subsequently expands away from the zone. Corresponding invalidation can be a sustained return to the old range, a close through the retest swing low, or an event-driven change in volatility and spreads that makes the original execution assumptions unusable.
Waiting for a retest may reduce the risk of chasing, but a clean breakout may never return. The first retest is not inherently safe either. Repeated visits can make a zone more visible while simultaneously consuming resting liquidity. Choosing between following a confirmed close and waiting for a retest is a trade-off between earlier participation and a higher evidence threshold, not a cost-free way to improve the win rate.
A lower-timeframe break can remain inside a higher-timeframe zone
A disciplined multi-timeframe process assigns three jobs. The higher timeframe defines the principal zones and market regime. The decision timeframe evaluates tests, acceptance and rejection. The lower timeframe refines execution and locates invalidation. A 15-minute close above a thin line does not mean daily resistance has disappeared; price may simply have moved from the lower edge of a broad daily zone to its upper edge.
Higher-timeframe areas are normally wider and slower to confirm. Lower timeframes reveal more detail but carry more spread, session and event noise. An unfinished daily bar can move in and out of “breakout” status several times. A backtest that uses the final daily close to direct trades earlier in that same day has introduced look-ahead bias. Analysis timeframe, intended holding period and invalidation horizon must refer to the same decision problem.
On FastBull Charts, mark the high-timeframe zone first, then step down to see how price enters, pauses and leaves it. Readers who need to revisit wick information, completed closes and swing structure can use Part 1: How to Read a Candlestick Chart as the common foundation.
Four markets, four different data problems
Forex: a data-release wick can be a feed and spread event
Setup. A central-bank decision, inflation release or labour report sends EUR/USD briefly through the edge of a range. Bid, ask and midpoint charts can print different extremes; providers may use different daily cut-offs; and spot FX tick volume measures feed-specific quote changes rather than total global turnover.
Confirmation. The continuation case improves only after liquidity and spreads return to executable conditions, completed bars still close outside the zone, most subsequent closes remain there and the ATR-scaled distance does not immediately collapse. Those observations indicate acceptance, not merely one exceptional quote.
Invalidation. If price quickly returns to the pre-release range and breaks the short-term structure created after the move, the breakout thesis has failed. The correct response is to withdraw the thesis, not automatically trade in the opposite direction.
Gold: spot levels cannot inherit futures-volume conclusions
Setup. XAU/USD crosses a prior high while activity changes in gold futures. Spot and futures are closely related, but their venues, sessions, prices and extremes are not identical. Centralised futures volume can inform participation; it cannot be described as the total volume of the global spot market.
Confirmation. Evidence strengthens when completed spot bars remain beyond the zone after the initial event shock, the area still qualifies after being rescaled to the new ATR regime, and price continues to build structure outside rather than relying on one long wick.
Invalidation. If expanded volatility carries price straight back into the old area, or the apparent break exists only on one spot or futures series, an event overshoot is more plausible than durable acceptance. The original confirmation standard must be downgraded.
Equities: an earnings gap may offer no trade near old resistance
Setup. An earnings announcement gaps a share above resistance. The chart appears to confirm a break at the old boundary, yet the first realistically available price may be far higher. Pre-market, after-hours and regular-session liquidity are different, and corporate actions can redraw adjusted history.
Confirmation. The case improves when regular-session trade remains above the zone, volume is strong relative to the same time of day, the close preserves the meaningful part of the gap, and the adjustment method has been checked so that the break is not an artefact of a split, dividend or other corporate action.
Invalidation. A gap fill followed by a close back in the old area invalidates the acceptance thesis. A test also cannot confirm the breakout at the close and simultaneously assume frictionless execution at that identical closing price.
Futures: a contract roll can manufacture a long-term breakout
Setup. A stitched continuous series jumps as the active month rolls, apparently clearing multi-year resistance. The individual tradable contracts may show no comparable move because their absolute prices reflect different delivery months and calendar spreads.
Confirmation. The relevant contract must display the same completed close and structural follow-through. Settlement conventions must be consistent, while volume and open interest should be migrating normally into the new active contract rather than signalling a data anomaly.
Invalidation. Discard the signal when it exists only in an adjusted continuous series or disappears on the tradable contract. Historical analysis must also include tick size, slippage, price limits and roll costs.
What volume and open interest can—and cannot—confirm
Rising volume means that participation increased; it does not by itself prove that “buyer money flowed in”, because every completed trade has both a buyer and a seller. Relative volume should compare current activity with a median for equivalent times of day, avoiding the mistake of treating naturally busy equity opens or futures sessions as exceptional. Spot-FX tick volume, exchange equity volume and contract-level futures volume are useful in different ways and should not be treated as interchangeable.
The change in futures open interest is:
ΔOI_t = OI_t - OI_(t-1)
Higher open interest means that more contracts remain outstanding, not that only new longs entered. Every open contract has a long and a short side. Rising price, volume and open interest together may suggest that new positions are participating, but they cannot guarantee further gains or identify every participant's motive. During a roll, falling open interest in the old contract and rising open interest in the next often reflects position migration rather than a directional signal.
Turn the zone into a falsifiable state machine
The largest improvement rarely comes from adding another indicator. It comes from defining what evidence each state requires before price reaches the area. The same sequence can support pre-trade planning, bar-by-bar replay and post-trade review:
| State | Evidence to record | Upgrade condition | Downgrade or invalidation |
|---|---|---|---|
| Zone marked in advance | Origin, boundaries, timeframe, quote and data convention | Price enters the volatility allowance | Adjustment or regime change removes comparability |
| Test | High and low inside the area, close location, volatility and session | A completed bar closes with its body beyond the boundary | Price rejects the area without changing structure |
| Breakout candidate | ATR-scaled excess, CLV, spread and executable liquidity | Most subsequent closes remain outside | Rapid re-entry into the old range |
| Acceptance outside | Time held, structural follow-through and relative activity | A new swing forms or a valid retest completes | Repeated closes return inside and structure breaks |
| Role reversal | Retest depth, reclaimed close and response structure | Price expands away from the zone again | The pre-defined retest swing fails |
Use the FastBull Economic Calendar to mark central-bank decisions, inflation, employment, inventories and corporate events before the test. Events do not erase every technical zone, but they alter volatility, spreads and execution. The appropriate response may be a wider research allowance, later confirmation or no decision at all during conditions in which the assumed trade could not have been executed.
Eight backtest errors that make levels look infallible
- Swing-confirmation look-ahead. A swing high normally needs bars to its right before it is confirmed. The test cannot assume the level was known on the high itself.
- Drawing after seeing the chart. Completed history makes successful zones obvious while failed and ambiguous candidates disappear from the sample.
- Unknown intrabar path. OHLC proves that the high and low occurred, but not whether price broke out, hit a stop or reached a target first.
- Same-close execution bias. The model confirms the signal at the close and then assumes an order filled at that same close with no friction.
- Parameter overfitting. ATR multipliers, zone widths and confirmation counts are searched repeatedly until the most flattering combination survives.
- Overlapping signals. Adjacent bars testing the same zone are counted as independent observations, inflating both sample size and confidence.
- Data-construction bias. Equity adjustments, FX cut-off times, spot-versus-futures differences and continuous-contract rolls are ignored.
- Missing costs and impossible fills. Spread, commission, slippage, gaps, financing, overnight charges, roll costs and price-limit constraints are omitted.
A useful report goes beyond “breakout win rate”. It should show median ATR-normalised returns over several horizons, maximum favourable and adverse excursion, the proportion of signals that re-entered the old area, time from break to invalidation, the observed frequency of retests, and out-of-sample results after costs. A result that collapses when neighbouring parameters change slightly has probably memorised noise.
The 30-second conclusion: draw support and resistance as justified areas with explicit boundaries and a volatility allowance. When price arrives, observe the intrabar test, completed close, acceptance outside, retest and structural invalidation in that order. A wick beyond the zone is not automatically a false breakout; a close beyond it is not automatically genuine. The value lies in specifying confirmation, invalidation, data conventions and executable conditions before the market reveals the answer.
Next in the series: volume, relative volume and open interest—what “high volume” can confirm, why every trade still has two sides, and why activity data cannot be compared across markets without understanding how it was constructed.
Risk notice: this article is for financial education only and is not trading or investment advice. Support, resistance, ATR, volume and historical backtests cannot guarantee future results. Any decision must also reflect personal objectives, risk tolerance, transaction costs and market liquidity.


