

How SOFR Futures Settle: Calendar Weighting, Compounding and the Rate Still to Be Fixed
 zhan chen
Five SOFR observations can cover seven days. Rebuild SR1 and SR3 reference rates, separate a 22.86-basis-point weighting mistake from a 0.13-basis-point compounding effect, and extract the remaining equivalent rate after part of the period has fixed.
A SOFR futures settlement check starts with the calendar, not with the average button in a spreadsheet. One-Month SOFR futures, or SR1, use a calendar-day arithmetic average. Three-Month SOFR futures, or SR3, compound interest in business-day blocks. Both can use the same daily benchmark, but they do not aggregate it in the same way. Once a reference period has begun, the futures-implied whole-period rate also includes interest that has already been fixed.
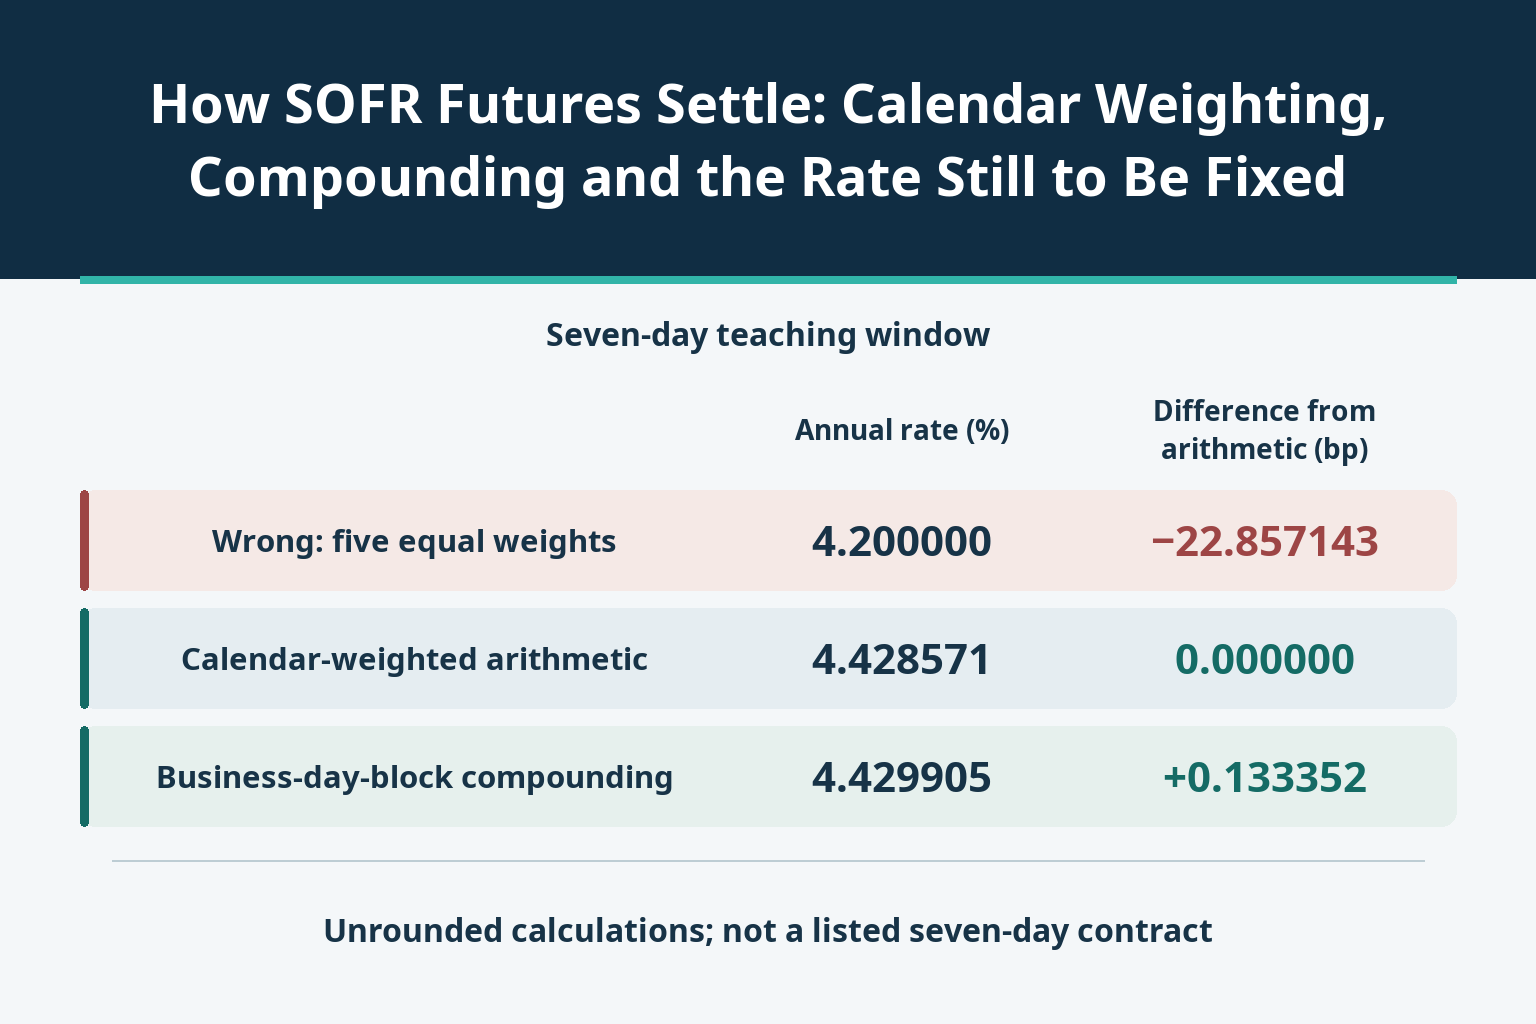
Those distinctions matter more than an extra decimal place. In the seven-day example below, ignoring weekend weights understates the arithmetic rate by about 22.86 basis points. Correct compounding adds only about 0.13 basis point. Treating both differences as a compounding adjustment would conceal the real error.
Start with the reference period, not the month printed on the quote
SR1 covers its contract calendar month. SR3 uses a reference quarter running from an included third Wednesday to an excluded third Wednesday three months later. A quarter is not automatically 90 days. The September 2026 SR3 contract, SR3U6, starts on September 16 and ends immediately before December 16: 91 calendar days. Its scheduled last trading day is December 15. The quoted contract name identifies the starting month; the rulebook’s delivery-month terminology identifies the ending month.
This is a calendar check, not a forecast of that contract’s settlement. It already catches two consequential mistakes: using September alone for SR3U6, or annualizing every reference quarter with a fixed denominator of 90. The actual number of covered calendar days belongs in the calculation. An official rolling 90-day SOFR average is not a substitute unless its endpoints and calculation conventions match the contract.
Five published observations need not mean five days of interest
Consider an invented Monday-to-Sunday window. SOFR is 4% on Monday through Thursday and 5% on Friday. The following Monday is a business day. Friday’s rate therefore covers three calendar days. The table assigns each day exactly once; the resulting total is seven, not five.
| SOFR value day | Assumed annual rate | Calendar days covered | Compounding factor for the block |
|---|---|---|---|
| Monday | 4.00% | 1 | 1 + 0.04 / 360 |
| Tuesday | 4.00% | 1 | 1 + 0.04 / 360 |
| Wednesday | 4.00% | 1 | 1 + 0.04 / 360 |
| Thursday | 4.00% | 1 | 1 + 0.04 / 360 |
| Friday | 5.00% | 3 | 1 + 0.05 × 3 / 360 |
This is a shortened laboratory for comparing aggregation methods, not a seven-day futures contract. Real implementations must also handle holidays and cut blocks off at the contract boundaries. If a reference window begins on a Sunday, only the Sunday inside that window belongs to the carried-forward rate; the preceding Friday and Saturday must not be added simply because the same fixing applies to them.
Keep the rate’s value day separate from its publication day. The New York Fed generally publishes SOFR around 8 a.m. New York time on the following eligible business day. A publication-date column shifted into a value-date column can move a Friday rate—and its heavier weight—to the wrong place. Use the U.S. government securities business calendar rather than a stock-exchange trading calendar.
SR1 adds weighted rates; SR3 multiplies accrual factors
Write each annual rate as a decimal r, so that 4% is 0.04. Let d be the number of calendar days covered by that fixing and D the sum of all d values. The arithmetic annual rate, expressed as a percentage, is 100 × Σ(r × d) / D. For the teaching window it is (4 × 4 + 5 × 3) / 7 = 4.4285714286%.
The compounded annual percentage is 100 × [Π(1 + r × d / 360) − 1] × 360 / D. Multiplying the five blocks gives (1 + 0.04 / 360)⁴ × (1 + 0.05 × 3 / 360) = 1.000861370406724, approximately. Subtract one and annualize over seven days to obtain 4.4299049489%.
Friday’s block accrues simple interest over three days. Compounding resumes between business-day blocks; it does not create new Saturday and Sunday reset events. Replacing Friday’s factor with (1 + 0.05 / 360)³ changes the contract method. A persistent rate is not the same thing as a new daily compounding observation.
Diagnose the size of the discrepancy before changing the formula
| Calculation | Unrounded annual rate | What the result tells us |
|---|---|---|
| Five observations, equal weights | 4.2000000000% | Incorrect: omits the weekend weight |
| Calendar-weighted arithmetic average | 4.4285714286% | Correct arithmetic aggregation for the teaching window |
| Business-day-block compounding | 4.4299049489% | Correct compounded aggregation for the teaching window |
| Compounding each weekend day separately | 4.4302027140% | Incorrect: changes the non-business-day convention |
The equal-weight calculation is (4 + 4 + 4 + 4 + 5) / 5 = 4.2%. Its shortfall relative to the correct arithmetic rate is 0.2285714286 percentage point, or 22.85714286 basis points. By contrast, correct compounding exceeds the arithmetic result by about 0.13335203 basis point. Incorrectly compounding each weekend day adds a further 0.02977651 basis point above the correct compounded result.
These are three different comparisons, with three different baselines. They should not be collapsed into a single unexplained “basis.” The extra digits expose the mechanisms; they are neither executable prices nor exchange-rounded settlement outputs. Nor does the small compounding difference establish a tradable SR1–SR3 spread: the listed contracts cover different periods and carry different dollar sensitivities.
A rate of 4.8% for the whole period is not 4.8% for the remaining days
Now use a separate synthetic 90-day period. Its first 45 days have a known cumulative factor A = 1.00625. Assume the price-implied target for the complete period is 4.8%, corresponding to an illustrative index of 95.2. The required complete-period factor is T = 1 + 0.048 × 90 / 360 = 1.012. The remaining factor must therefore be T / A = 1.005714285714286, approximately.
To make the remaining-rate calculation reproducible, specify its calendar: the sequence of day weights [1, 1, 1, 1, 3] occurs six times, followed by [1, 1, 1]. Those 33 blocks cover 45 days. Solve Π(1 + r × d / 360) = 176 / 175, the exact value of T / A, for a single constant r. The solution is approximately 4.5589363869% a year, not 4.8%.
A is an assumed aggregate of known accruals, not a claim about historical fixings. The 90-day calendar is also synthetic; it does not replace the 91-day SR3U6 calendar above. The result answers a narrow question: what constant future rate would reconcile this known factor, this remaining calendar and this whole-period target? Dividing a percentage into two equal halves, or subtracting one rate from another, does not perform that reconciliation.
As the unfixed portion gets shorter, a small change in the whole-period target can require a larger change in the remaining equivalent rate, with known accruals held constant. A quiet-looking full-period quote should not therefore be read as an equally small change in expectations for the days still ahead.
Many changing future paths can produce the same remaining factor. The constant is not a prediction of every fixing, a real-world probability-weighted expectation or an implied probability for one policy meeting. SOFR measures secured overnight Treasury financing, not the central bank’s target range itself. A meeting-probability model would need additional assumptions that this calculation does not supply.
Only then convert the rate into an index and a cash result
The index convention is 100 minus the annual rate expressed in percentage terms. A rate of 4.8 means 95.2, not 99.952. A one-basis-point rise in the contract reference rate lowers the index by 0.01 point. Its dollar value is $41.67 for one SR1 contract and $25 for one SR3 contract. This sensitivity concerns the complete contract rate; a one-basis-point shock to a single daily fixing is diluted by its calendar weight and, for SR3, the other accrual factors.
Final cash settlement does not mean the holder deposited a principal amount and receives the entire reference-period interest. Futures gains and losses follow index changes and variation settlement. Equally, rebuilding the terminal reference rate is a different task from understanding how an exchange determines a daily settlement price.
Preserve calculation precision through the aggregation, then apply the final-rounding convention valid for that contract and delivery. Do not infer it from the trading tick. An announced rule change must be checked against its applicable contracts rather than a headline date. The examples here deliberately stop before contract-specific final rounding. For the terminal SOFR observation, CME specifies the first published value; blindly replacing every observation with a subsequently downloaded history can therefore break an otherwise correct reconciliation.
A five-step settlement audit that can actually find the error
- Identify the contract and endpoints. Record the included start, excluded end and D. Keep the quoted contract month separate from a rulebook delivery month.
- Build the fixing ledger. Save value dates, publication dates, rates and applicable data versions. Map every in-window calendar day to exactly one fixing.
- Choose the aggregation. Use the weighted arithmetic sum for SR1 and business-day-block factors for SR3. Check percentage-to-decimal conversions and the 360-day basis.
- Separate known and unknown accruals. For a partly fixed compounded period, divide the target factor by the known factor. Label any constant-rate solution as an assumption, not a forecast.
- Reconcile the final output. Apply the contract’s valid rounding rule, subtract the percentage rate from 100, and check dollar sensitivity separately from daily cash movements.
If a result still differs, inspect the calendar, data version and units before reaching for a market explanation. An omitted weekend, a misplaced fixing or a mismatched reference quarter is a reproducible error—not evidence of a policy surprise or an arbitrage opportunity.


