

FX Settlement Risk: Why a $200,000 Replacement Cost Can Hide $11 Million of Principal Exposure
 zhan chen
Payment versus payment protects the exchange of currency principals, not every funding need. A worked EUR/USD example separates replacement cost from principal exposure, measures a 25-hour monitoring window and shows why payment netting is not PvP.
A foreign-exchange trade can have a replacement cost of USD200,000 while exposing USD11 million of principal during settlement. Those figures answer different questions. The first asks what it costs to recreate the bargain; the second asks how much has been paid away before the purchased currency has been finally received.
Payment versus payment, or PvP, addresses that second problem by making the two final currency transfers conditional on each other. It does not promise that a transaction will settle on time, that replacement currency will be cheap, or that every prefunded dollar will immediately be available again. The distinction becomes clearer when the trade, the payment timeline and the netting agreement are examined separately.
Start with two currency principals, not one profit-and-loss number
Assume institution A buys EUR10 million for USD11 million, agreeing 1.10 dollars per euro. This is a deliverable exchange: A must pay dollars and receive euros. It is not a contract that simply pays a dollar difference. A screen showing a small market-value change does not replace either principal obligation.
For a replacement calculation, assume A can buy the entire EUR10 million for the same value date at an executable rate of 1.12 USD/EUR. The replacement payment is USD11.2 million. Compared with the original USD11 million payment, the additional cost is USD200,000. The rate is a hypothetical price for A's direction and size, not a live quotation or an arbitrary midpoint.
The model excludes fees, discounting, taxes, collateral and recoveries. Those items would need separate treatment in a real assessment. Crucially, the payment status must be established before deciding which of these amounts belongs in the risk report.
Replacement cost and principal exposure describe different states
First consider a trade confirmed cancelled before A pays any principal. A still needs the euros, and the replacement purchase now costs USD200,000 more. This is positive replacement cost. The fact that the new trade requires USD11.2 million does not turn that full payment into an incremental loss: A receives EUR10 million in exchange.
Now consider a separate state. Without PvP, the original USD11 million has been finally paid, but A has not finally received the euros. The relevant principal exposure is USD11 million, not merely the USD200,000 difference between exchange rates. Calling it exposure does not assert that the counterparty has defaulted or that recovery will be zero.
| Transaction state | What has happened | The amount being measured | What it does not establish |
|---|---|---|---|
| Original trade confirmed cancelled before payment | A still needs to buy EUR10m at the assumed 1.12 USD/EUR | Positive replacement cost: USD200,000 | The original USD11m principal has not been paid away; this is not a paid-principal loss |
| USD paid first without PvP | USD11m is finally paid; EUR10m has not been finally received | Principal exposure: USD11,000,000 | Exposure is not an established final credit loss |
| PvP conditions are not met | Neither final currency exchange takes place | One-sided final-exchange principal exposure: USD0 | Replacement cost and currency funding needs can remain |
The table compares alternatives; its rows are not consecutive losses to add together. Nor is USD11 million an absolute ceiling on every possible economic consequence. Replacement execution, funding costs and eventual recoveries require their own assumptions and loss definitions. A sound report preserves those distinctions instead of producing a misleading single total.
PvP can protect the exchange and still leave a currency shortage
Under the third state, the PvP conditions are not met and neither final currency transfer occurs. There is no one-sided final exchange in which A has paid its dollar principal but has not received the euro principal. That is the protection being tested—not a claim that every risk associated with the transaction or service has disappeared.
Suppose, additionally, that A must make a separate EUR10 million payment that day and has no other available euros. If the exchange does not settle, that EUR10 million obligation is still due. A may need replacement execution or euro financing. At the assumed replacement price, buying the currency costs USD11.2 million, USD200,000 more than originally agreed. Neither access to credit nor its price is guaranteed.
The EUR10 million shortage is a currency-and-time requirement, not automatically another EUR10 million of net loss. Without the separate payment obligation, the example establishes euros not received, not an immediate overdue bill. Likewise, PvP does not by itself prove that money previously placed with a settlement service is instantly returned and reusable. Availability and service-provider credit exposure must be checked separately.
The monitoring clock can start before the cash leaves
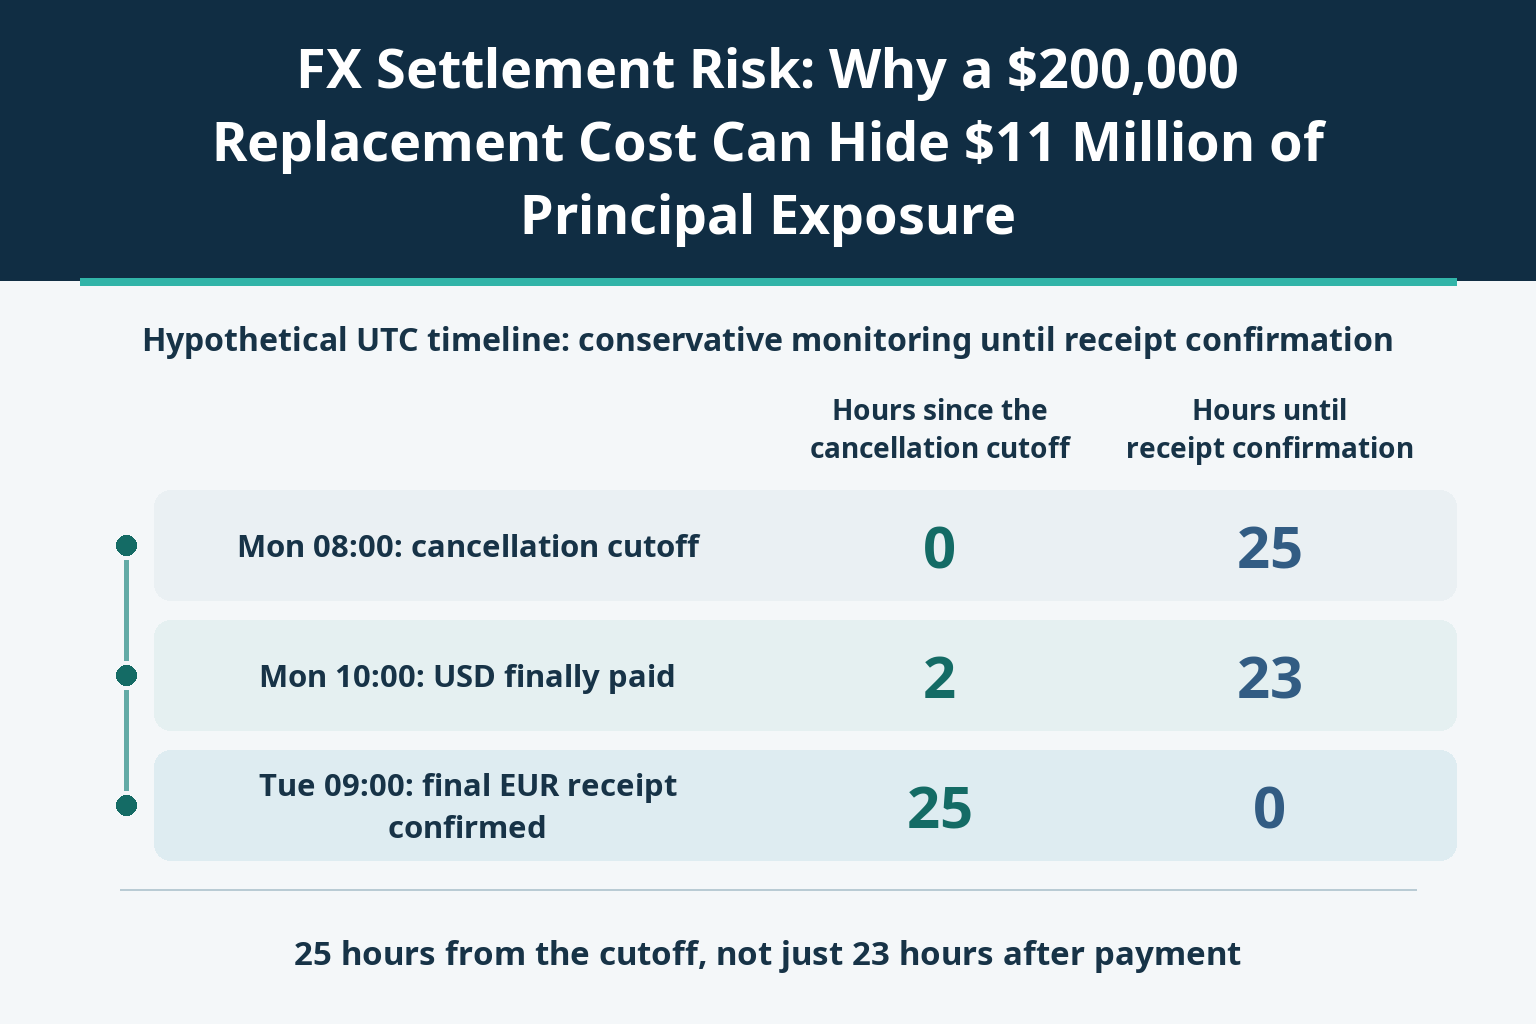
Use a wholly hypothetical UTC timeline. At 08:00 on Monday, A can no longer guarantee unilateral cancellation of its dollar instruction. The dollars are finally paid at 10:00. At 09:00 on Tuesday, A confirms and reconciles final receipt of the euros. These times are not the timetable of any particular settlement provider.
Conservative monitoring from the cancellation cutoff to confirmed final receipt covers 25 hours. Measuring only from actual payment covers 23 hours and omits the earlier two-hour interval in which A could no longer rely on stopping its instruction by itself. A planned same-day receipt is not a substitute for actual settlement evidence.
Two qualifications matter. Losing a guaranteed unilateral cancellation right does not mean an agreed recall can never succeed. And the actual principal risk ends when receipt becomes final, not when an employee later reconciles it. If reliable records establish an earlier final receipt, the actual endpoint should be updated. A reconciliation delay creates uncertainty; it is not evidence of an additional realized principal loss.
Netting reduces the dollars to pay, but leaves two currency legs
Add a second transaction with the same counterparty and value date: A pays EUR7 million and receives USD7.77 million. Assume a legally effective, enforceable payment-netting arrangement covers both trades. Netting is performed separately within each currency. Positive numbers below mean receipts by A; negative numbers mean payments by A.
| Transaction | A receives (+) / pays (−), EUR millions | A receives (+) / pays (−), USD millions |
|---|---|---|
| First trade | +10 | −11 |
| Second trade | −7 | +7.77 |
| Per-currency net amounts under the effective agreement | +3 | −3.23 |
A's net amounts are a USD3.23 million payment and a EUR3 million receivable. The outgoing dollar amount falls by USD7.77 million, from USD11 million to USD3.23 million—a reduction of about 70.64%. The net row is the result of the agreed netting process, not a newly executed third transaction.
If the net dollars are finally paid without PvP and the net euros have not been finally received, USD3.23 million can still be exposed. Reducing the principal is valuable, but it is not the same as linking final transfer of both legs. Converting the EUR3 million receivable to a screen dollar value and subtracting it again does not discharge the counterparty's obligation to deliver euros.
This arithmetic also cannot authorize netting between different counterparties, value dates or agreement scopes. Without an effective arrangement, a treasury spreadsheet does not rewrite gross payment obligations.
A matched trade, a CCP and PvP provide different evidence
Trade matching establishes agreement on trade details; it does not prove final receipt. A central counterparty interposes itself as counterparty. Payment netting reduces amounts before settlement. Close-out netting addresses termination following a specified event. PvP links the final transfer of two currencies. One label does not establish the presence of all the other functions.
The operational test is transaction-specific: which payment route will this trade use, which currencies and products does it cover, and what records establish finality? Two instructions scheduled for the same clock time are not enough. Nor is a familiar service-provider name sufficient evidence that a particular trade has PvP protection.
The distinction also explains why a forward's replacement value before maturity is not a complete measure of principal at risk during delivery. Valuation asks what the contract is worth; the settlement ledger asks what can no longer be stopped, what has finally left and what has finally arrived. Both views are necessary, but they should not be collapsed into one number.
Five checks before relying on the settlement plan
- Reconstruct both currency legs, amounts and value date. Establish whether the contract delivers principals or only settles a difference.
- Record cancellation cutoffs, final-payment evidence, final-receipt evidence and reconciliation separately. Put all timestamps in one time zone.
- Verify the actual PvP route for the transaction. Do not infer coverage from matching, a provider's brand or an unrelated netting service.
- Check the enforceable payment-netting scope by counterparty, currency and date. Keep the residual obligations distinct from close-out or CCP arrangements.
- Test the currency needed at each deadline if settlement fails. Confirm replacement prices, available funds and access to any prefunded balances rather than assuming automatic availability.
The useful sequence is to identify the principals, reduce eligible payment amounts, determine whether final transfers are linked, and then fund any remaining timing gap. A low replacement value cannot answer all four questions. Neither can the comforting but incomplete statement that a trade has been matched or netted.


