

Futures Funding Costs: Same Entry and Exit Prices, Different Cash Results
 zhan chen
A futures round trip can have zero gross trading P&L and still consume cash. Reconstruct two opposite variation-payment paths, test whether gains are actually available, and separate loan principal from interest and initial-margin carry.
Sell a futures contract at 96 and buy it back at 96: the price-based trading result is zero before costs. That does not mean the position used no cash. If a loss had to be paid weeks before an offsetting gain arrived, somebody had to finance the interval. Reverse the order of those transfers and the same entry and exit prices can leave a different cash result.
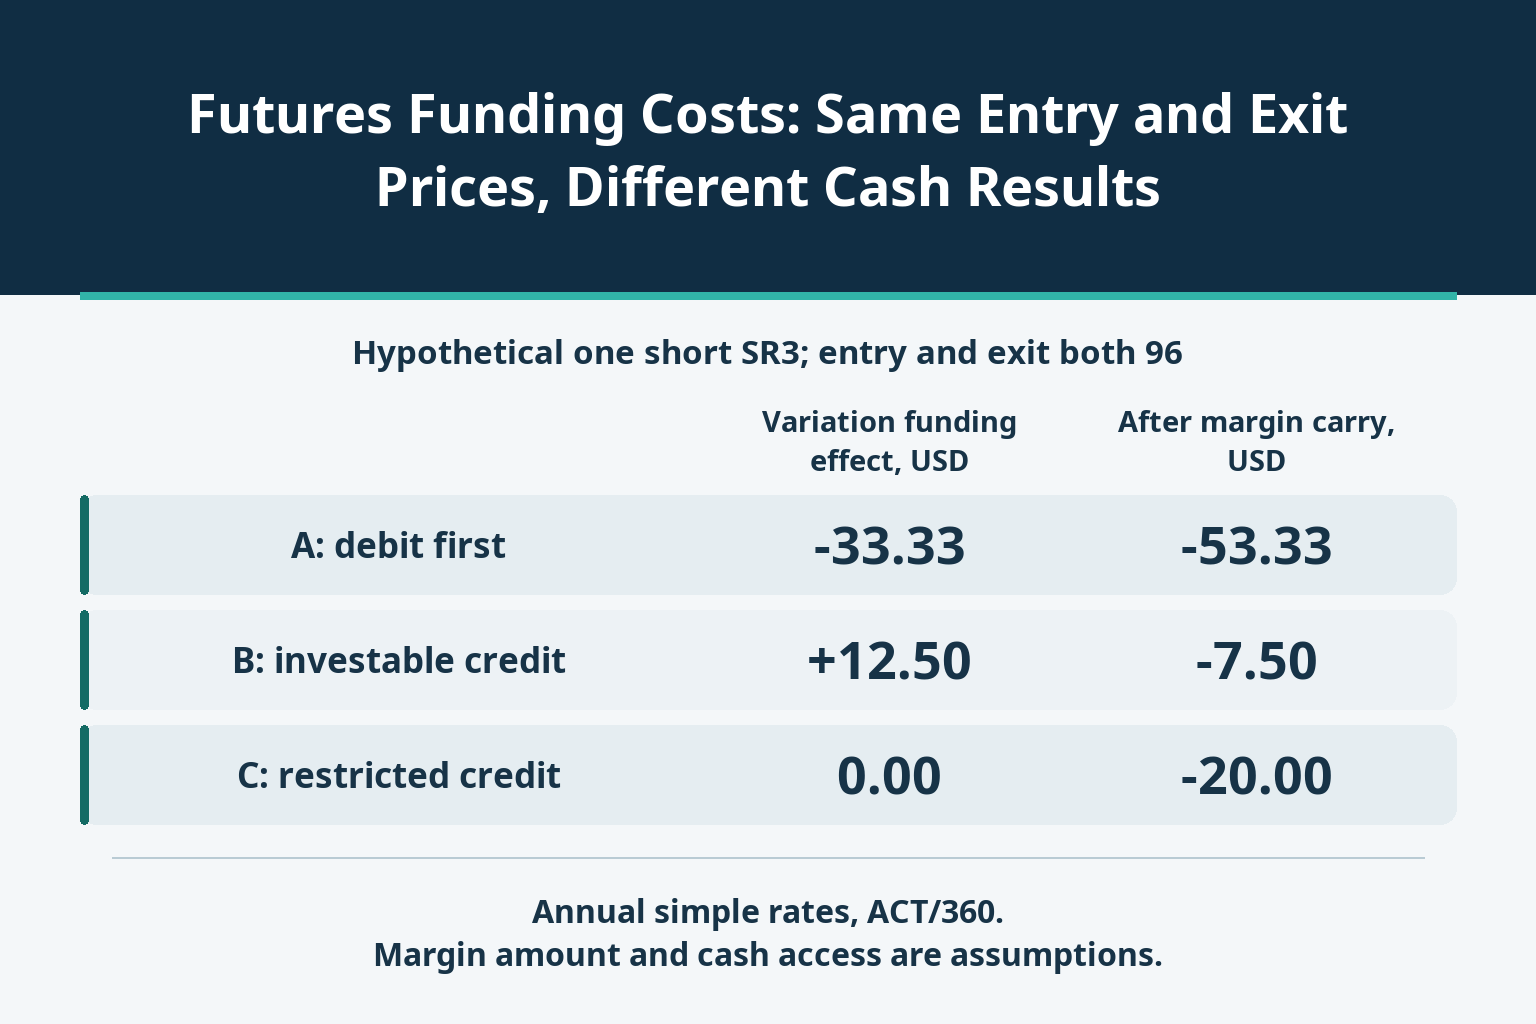
The missing variable is the sequence of usable cash, not another forecast of the closing price. In the hypothetical short SOFR futures position below, variation funding contributes either −USD 33.33, +USD 12.50 or zero, depending on the path and access to a credit. A separate, explicitly assumed collateral-financing cost then changes the total results to −USD 53.33, −USD 7.50 and −USD 20.00. None of these figures is a current broker quote or a market return forecast.
Fix the contract, direction and cash dates first
CME's Three-Month SOFR futures contract, SR3, has a value of USD 25 per annual-rate basis point, equivalent to USD 2,500 per full IMM price point. Its quotation follows the 100-minus-rate form. A short therefore loses when the futures price rises; confusing the direction of the quoted rate with the direction of the price reverses the cash ledger.
CME's clearing calculation explains daily cash settlement variation using the trade price or preceding settlement price and the current settlement price, with the position's sign applied. This clearing mechanism does not establish when a customer's broker permits a withdrawal. A credit on a statement and dollars available for an outside payment can be different things.
Assume one short SR3 is opened at 96 on day 0 and closed at 96 on day 90, before expiry. These day numbers are invented customer cash dates, separated by actual calendar days, not named trading dates or a 90-business-day schedule. Prices are unchanged between the displayed jumps, and closing at 96 is assumed executable. Fees, taxes, foreign exchange and execution costs are omitted. This ledger is separate from the compounded-rate calculation that determines final SOFR futures settlement.
| Hypothetical path | Day 30 futures price | Day 30 variation, USD | Day 90 variation, USD | Gross trading P&L, USD |
|---|---|---|---|---|
| A: debit first | 97 | -2,500.00 | +2,500.00 | 0.00 |
| B: investable credit first | 95 | +2,500.00 | -2,500.00 | 0.00 |
| C: restricted credit first | 95 | +2,500.00 | -2,500.00 | 0.00 |
Follow the loan when the loss arrives first
In path A, the day 30 settlement price rises from 96 to 97. One short contract pays 1 × USD 2,500 = USD 2,500. That is a full price point, not a one-basis-point movement worth USD 25. Assume the payment must be funded that day, no other cash is available for it, and a separate loan can be drawn at an invented annual simple rate of 8%.
The price returns to 96 on day 90, producing a USD 2,500 variation receipt. The borrowing interval is 90 − 30 = 60 actual calendar days. Under the stipulated ACT/360 convention, loan interest is 2,500 × 0.08 × 60/360 = 100/3, approximately USD 33.33.
The loan draw on day 30 is not income: it finances the variation payment. On day 90, the USD 2,500 receipt repays USD 2,500 of principal, but the interest still has to be paid. The remaining variation-funding result is −USD 33.33, not a second USD 2,500 trading loss. Equally, the later receipt is not USD 2,500 of new net profit after ignoring the earlier debit.
This outcome assumes the position survives to the modeled reversal. If it is closed at 97 on day 30, the gross trading loss is USD 2,500. The imagined day 90 recovery cannot finance a payment due now, and it cannot rescue a position already closed.
A credit helps only if its use is permitted
Path B reverses the price sequence: 96 becomes 95 on day 30 and returns to 96 on day 90. The short first receives USD 2,500, then pays USD 2,500. Assume the entire first credit is available immediately, can be invested outside the margin account and is not needed for another claim before the final debit.
At an invented annual simple investment rate of 3%, the 60-day proceeds are 2,500 × (1 + 0.03 × 60/360) = USD 2,512.50. Paying the day 90 variation debit leaves USD 12.50. The investment principal is not profit; it must be brought back in time to meet the payment. A security that can only be sold later, or at an uncertain price, does not satisfy the assumed cash availability.
Path C has exactly the same futures prices and variation credits as B, but the credit cannot be withdrawn or pledged and earns no interest. It remains in the account and is available there to satisfy the day 90 debit. Its incremental funding contribution is zero. If an actual restriction also prevented that use, a new financing requirement would arise; it is not covered by C as defined. These are alternative account arrangements, not claims about a universal brokerage policy.
Keep initial-margin carry in its own account
Now add a deliberately separate collateral layer. Assume USD 2,000 of initial margin is posted on day 0 and released on day 90. This is an invented amount, not an actual SR3 margin requirement or a promise of release timing. A fixed 90-day loan funds it at an annual simple 6%, while the pledged cash earns an assumed annual simple 2%, both ACT/360.
Loan interest is 2,000 × 0.06 × 90/360 = USD 30. Collateral remuneration is 2,000 × 0.02 × 90/360 = USD 10. The net carry cost is USD 20. At the end, the returned USD 2,000 repays the loan principal. Neither posting nor returning that principal is an additional trading loss or gain.
A crucial policy assumption makes the same USD 20 applicable to all paths: this loan remains drawn for the full 90 days and is not repaid early under the modeled arrangement. B's accessible credit is invested separately rather than used to retire the 6% loan. No cross-netting is assumed. This is a transparent cash-management constraint, not a claim that investing at 3% while borrowing at 6% is optimal. If repayment and later redrawing are allowed, recalculate the whole funding policy instead of retaining the same cost mechanically.
Actual collateral requirements can change. CME distinguishes initial and maintenance requirements and explains that risk conditions affect margin. Historical dollar examples do not establish today's requirement, and a broker's account terms can impose additional constraints. The fixed collateral assumption isolates this example's funding mechanism; it does not eliminate margin risk.
Reconcile net cash without calling principal a cost
| Hypothetical path | Variation funding effect, USD | Initial-margin carry cost, USD | Total net result, USD | Peak borrowed principal, USD |
|---|---|---|---|---|
| A: debit first | -33.33 | 20.00 | -53.33 | 4,500.00 |
| B: investable credit first | +12.50 | 20.00 | -7.50 | 2,000.00 |
| C: restricted credit first | 0.00 | 20.00 | -20.00 | 2,000.00 |
After subtracting the common USD 20 carry, A ends at −160/3, approximately −USD 53.33; B at −USD 7.50; and C at −USD 20.00. B's positive investment contribution does not make its total result positive. All three still have zero cumulative gross futures P&L.
A needs USD 2,500 of variation borrowing in addition to the USD 2,000 collateral loan. Its maximum simultaneous borrowed principal is therefore USD 4,500 in this controlled ledger. B and C need USD 2,000 of external principal under their stated arrangements. Those figures exclude accrued interest and are not safe capital budgets, maximum losses or margin caps. Interest still requires cash at the end; the model pays it then without additional interest on interest.
Interim calls, changed house collateral, funding-line limits and delayed receipts could increase the actual requirement. Keep this liquidity measure separate from profit. Do not add the final price-based P&L again after already summing all variation payments, or deduct every loan repayment as an expense while counting the original borrowing as revenue.
The timing effect is not merely the borrowing spread
For an initial debit V financed for d days at annual simple rate b, the contribution is −Vbd/360. An accessible initial credit V invested at rate a contributes +Vad/360. Between these symmetric price paths, the difference is V(a + b)d/360, not V(b − a)d/360. Here it is 2,500 × (0.03 + 0.08) × 60/360 = 275/6, approximately USD 45.83. The identical collateral cost cancels when comparing B with A.
Even setting both rates to 3% leaves −USD 12.50 for the debit-first path and +USD 12.50 for the investable-credit path. Equal rates do not remove the economic effect of opposite cash timing. If both rates and collateral carry were zero, these controlled cash results would reduce to the zero gross trading result.
These are realized hypothetical paths, not probability-weighted fair values. No distribution, discount curve or rate covariance has been supplied. Dividing USD 45.83 by a contract's USD 25 basis-point value therefore does not estimate a market futures-versus-forward-rate-agreement adjustment. Nor does a calculation using a fixed USD 20 cost justify extending the holding period: extra time changes collateral carry, possible calls and the price path itself.
Five checks turn a price result into a cash result
- Verify direction and multiplier. Record the exact contract, quantity and entry, daily settlement and exit prices. Check that cumulative variation reconciles to the gross price-based result without treating an index point as a basis point.
- Record customer cash dates. Separate a clearing credit, a broker ledger entry, withdrawal permission and the payment cutoff. Confirm what cash can actually be invested, pledged or used for a later debit.
- Describe every financing leg. State annual rates, day counts, compounding, draw and repayment dates, early-repayment rights and maturity availability. Net loan and investment principal correctly; test an alternative cash policy if funds are fungible.
- Stress collateral and funding capacity separately. Add actual broker requirements, fees, intraday calls and delayed releases. Compare committed liquidity with principal and interest due, not just with a favorable final-price scenario.
- Close the account at the chosen horizon. Reconcile variation, returned collateral, investment redemption and all loan repayments. Also examine an early exit: an assumed future reversal is not available funding and is not a reason to leave a deficient account unresolved.
Identical entry and exit prices answer the gross trading question. A cash decision also needs to know who paid first, for how long, under which funding arrangement, and whether credited money could actually be used.


