

Equal Forex Lots Are Not a Dollar Hedge: Rebuild the Currency Legs
 James Riley
A long EUR/USD and a short GBP/USD of one lot each can leave unequal dollar notionals. Rebuild the currency quantities, test a common 1% move and separate an initial dollar offset from the relative-currency risk that remains.
Buying EUR/USD and selling GBP/USD does not automatically cancel a dollar view. A lot counts base-currency units, not a constant dollar amount: 100,000 EUR and 100,000 GBP are different quantities with different dollar values. Opposite trade directions are not enough to establish an offset.
The useful question is specific: which currency quantities does the portfolio represent, at which reference rates, and how would its value change under a stated shock? An initial notional match answers one narrow question. It does not demonstrate a risk-free trade, a permanent hedge or an automatic reduction in required margin.
Translate the tickets into currency quantities
Assume a USD account, linear FX profit and loss, and a contract size of 100,000 base-currency units per lot for both pairs. The reference rates are invented: EUR/USD=1.1000 and GBP/USD=1.2500. Start without spreads, financing, fees or execution differences so the exposure calculation can be checked separately from costs.
A long 100,000 EUR position represents +100,000 EUR and −110,000 USD at entry. A short 100,000 GBP position represents −100,000 GBP and +125,000 USD. Group quantities by currency rather than adding the two lot counts.
| Entry ticket or total | EUR units | GBP units | USD units |
|---|---|---|---|
| Long 1.00 EUR/USD | +100,000 | 0 | −110,000 |
| Short 1.00 GBP/USD | 0 | −100,000 | +125,000 |
| Equal-lot total | +100,000 | −100,000 | +15,000 |
The portfolio has a +15,000 USD residual in this economic decomposition, alongside a long EUR and a short GBP exposure. These are analytical currency legs, not a statement that a leveraged account physically received or borrowed these deposits. The platform’s cash balance and exposure display can use a different account model.
Size the stated dollar offset, not an unspecified “hedge”
To match the initial 110,000 USD value of the EUR leg, the GBP quantity is 110,000÷1.2500=88,000 GBP. Under the assumed contract size this is 0.88 lot. It leaves +100,000 EUR, −88,000 GBP and zero net entry USD in the decomposition.
That is an initial dollar-notional matching ratio. It is not a minimum-variance hedge ratio derived from volatility and correlation, a broker’s margin offset, or a recommendation to place a particular trade. Different objectives require different measurements.
Do not replace the two base amounts with a rule such as “one long and one short cancel.” Nor should 0.88 be stored as a universal constant: changing the reference rates, the EUR quantity or either contract size changes the required ticket quantity.
Run the same shock through both portfolios
First let both dollar quotes rise by exactly 1% from entry: EUR/USD becomes 1.1110 and GBP/USD becomes 1.2625. This is a specified common shock, not a forecast that the two currencies move together.
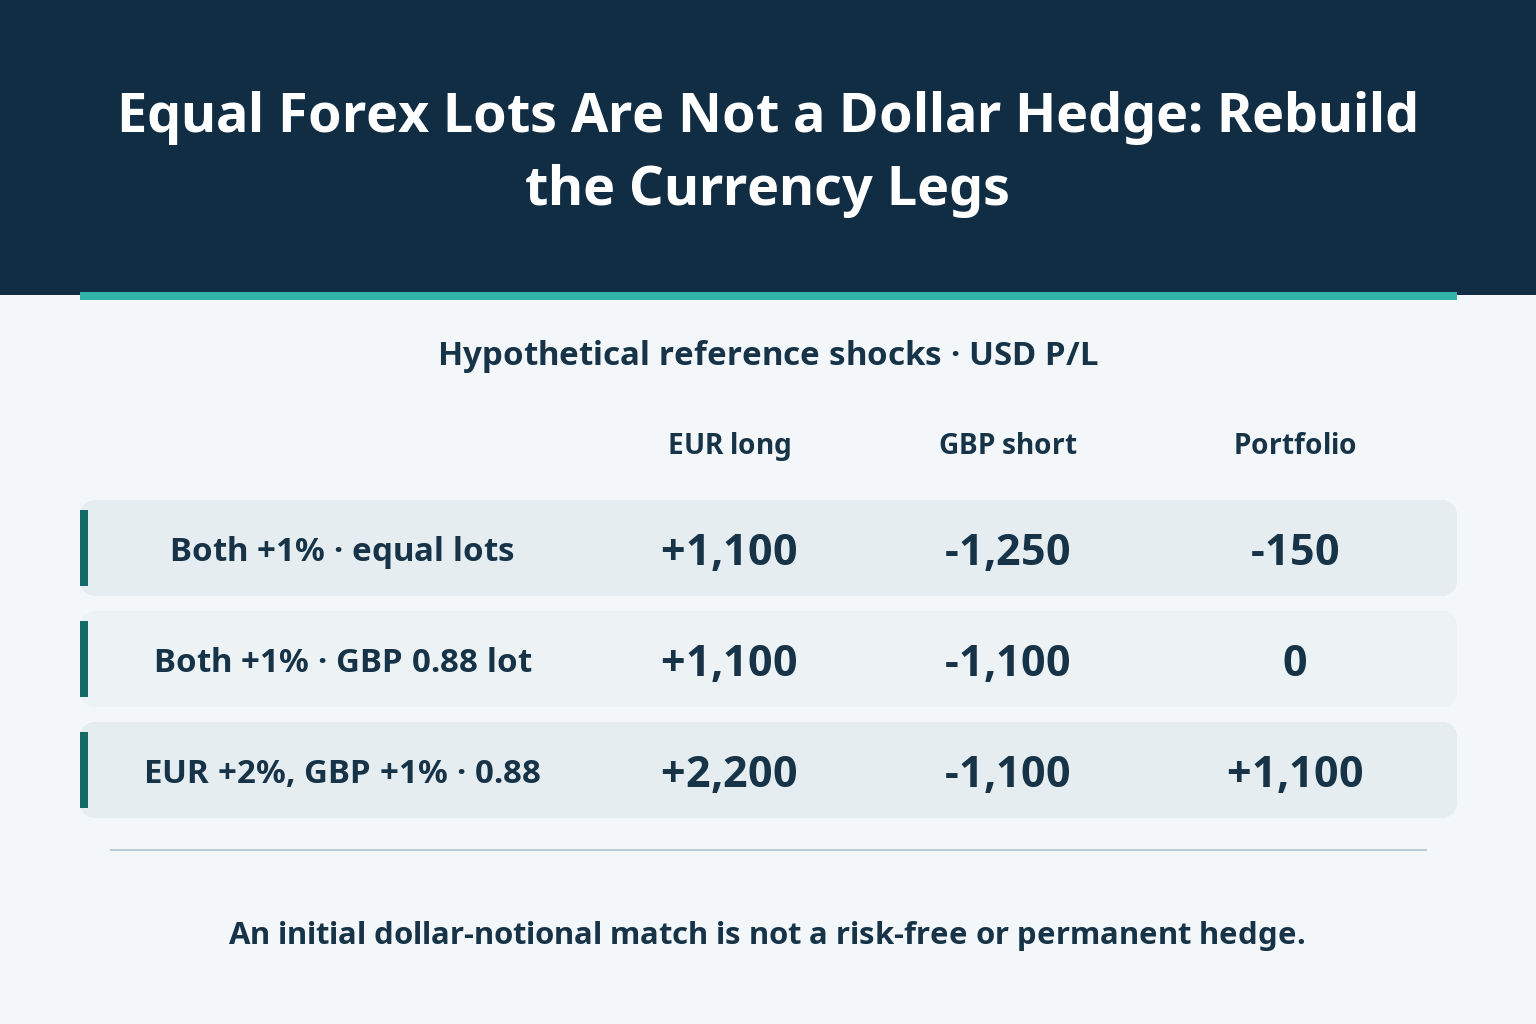
The EUR leg earns 100,000×(1.1110−1.1000)=1,100 USD. The 100,000 GBP short loses 1,250 USD; the 88,000 GBP short loses 1,100 USD. Thus the equal-lot portfolio loses 150 USD while the initial matched-notional portfolio has zero price P/L in this particular test.
| Independent reference scenario | EUR long P/L, USD | GBP short P/L, USD | Total, USD |
|---|---|---|---|
| Both +1%; 1.00 GBP lot | +1,100 | −1,250 | −150 |
| Both +1%; 0.88 GBP lot | +1,100 | −1,100 | 0 |
| EUR +2%, GBP +1%; 0.88 GBP lot | +2,200 | −1,100 | +1,100 |
Zero in one row is not a guarantee. In the independent second scenario, EUR/USD rises 2% to 1.1220 while GBP/USD rises 1% to 1.2625. The matched portfolio earns 2,200−1,100=1,100 USD before costs. Reversing the relative performance can produce a loss.
Zero entry dollars still leaves a relative-currency position
The matched portfolio still owns economic EUR exposure against GBP. Its reference EUR/GBP ratio starts at 1.1000÷1.2500=0.8800 and becomes approximately 0.888713 in the second scenario. The remaining risk is the relative movement of the two currencies, not a missing spreadsheet line.
A quotient of reference rates is not an executable cross-rate quote. Actual bid and ask sides, timestamps and dealing costs matter. Do not present the reference calculation as a costless arbitrage opportunity or promise the same realised result from a direct cross trade.
The initial dollar match also does not remain exact after arbitrary rate moves. At a later timestamp, a common proportional-shock test uses 100,000×current EUR/USD minus 88,000×current GBP/USD. After the independent second scenario the difference is 1,100 USD, so another common 1% increase would add 11 USD of price P/L, not zero, with quantities unchanged.
Economic offsets do not settle execution, margin or account conversion
Rebalancing can change the subsequent exposure, but creates new trades, spreads, fees and potential slippage. It does not remove the P/L already earned or lost. Financing costs on the two positions need not offset even when an initial dollar leg does.
The account’s margin rules must be checked separately. Different products, entities, hedging modes or tiered requirements can prevent a collateral offset. A broker can close one leg before the other; an economically paired position is not proof that both legs will be filled or liquidated together.
For a non-USD account, dollar P/L must also be converted under the actual account rules. The conversion currency can add another sensitivity. A portfolio spreadsheet is not a substitute for the broker’s timestamped account, financing and execution records.
A reproducible review before calling the position diversified
List each ticket’s direction, base units per lot, quantity and reference timestamp. Split every ticket into signed base and quote quantities, then sum each currency separately. Keep existing cash balances distinct from trade legs unless the scope explicitly includes them.
Revalue the unchanged quantities under at least a common quote shock and a relative-currency shock. State whether prices are reference values or executable sides, whether costs are included, and which currency measures the result. Reconcile the result with the actual statement rather than forcing it to match an advertised hedge label.
Finally check quantity increments, contract definitions, financing schedules, margin offsets and independent-leg closure risks. Use position sizing from a defined account-risk budget to connect the portfolio result to an account-level loss budget; several tickets can share a risk driver even when each is small on its own.


