

COMEX Gold Delivery: Why the Invoice Is Not 100 Ounces Times Your Entry Price
 zhan chen
Reconcile a GC delivery invoice with fine gold weight, the applicable settlement price and cumulative futures cash flows. Three alternative bars and a falling-price example show when the original entry price does—and does not—lock the final cost.
A profitable gold futures position does not pay for the metal by itself. A buyer taking delivery still has to fund the delivery invoice. Nor is that invoice necessarily 100 multiplied by the original futures price: the standard contract's price exposure, the fine gold represented by a warrant and the price used for delivery are three separate inputs.
In the example below, one GC long earns $10,000 before delivery, but the metal invoice is $258,700. Their accumulated difference is $248,700—not the $250,000 suggested by multiplying the entry price by 100. The discrepancy is traceable to quantity, not a missing profit payment. It also does not establish that the buyer received 100 fine ounces at a discount.
Separate the contract unit from the gold being billed
Standard COMEX Gold futures, identified as GC, have a trading unit of 100 troy ounces. The delivery rules allow a weight tolerance of 5% above or below that standard and require at least 995 parts per thousand, or 99.5%, fineness. Approved brands, documents and custody arrangements also matter; weight and purity alone do not make an arbitrary bar deliverable. These are GC rules, not a description of every gold futures product.
The relevant distinction is gross bar weight versus fine gold weight. A hypothetical bar weighing 100.000 troy ounces at 0.995 fineness contains 99.500 fine troy ounces. CME's official delivery illustration explicitly uses fine weight as the invoice basis. A minimum fineness requirement does not mean every deliverable bar has exactly that fineness, so the actual warrant and supporting records must supply the inputs.
Use G for recorded gross weight, f for fineness expressed as a fraction, and W for fine ounces billed. The simple relationship is W = G × f. Our inputs make that product exact to three decimal places and all metal amounts exact to cents. This avoids assuming an undocumented rounding sequence for every possible bar. Do not substitute ordinary avoirdupois ounces, or round an unfamiliar weight field merely to make the invoice match.
The delivery reference price is not your entry price
The normal delivery-price basis under Rule 706.D is the settlement price on the day the notice of intention to deliver is submitted. There is a month-end exception: an intention submitted on the next-to-last business day of the delivery month uses the settlement price from the third-to-last business day. The notice date therefore matters; neither the purchase date nor an arbitrary latest trade determines the invoice.
The difference between an official reference and the last trade is explored in how deferred futures settlement prices are constructed. That separate pricing example does not replace the GC delivery rule: here the applicable date and contract still have to match the invoice.
Call the entry price F0 and the applicable delivery reference P. For an unchanged one-contract long, assume its futures ledger has been reconciled through that same P, including any required clearing price adjustment. Its cumulative futures result is 100 × (P − F0). This combines earlier variation-margin cash flows; it is not a new profit that should be paid a second time on delivery.
That reconciliation condition is essential. If a statement ends at a different settlement price, first locate the remaining adjustment rather than subtracting an incomplete profit figure from the delivery invoice. Rolling the position, changing contract count or closing part of it also requires the actual trade-by-trade ledger, not this one-contract shortcut.
Reconcile three alternative bars, not three delivered bars
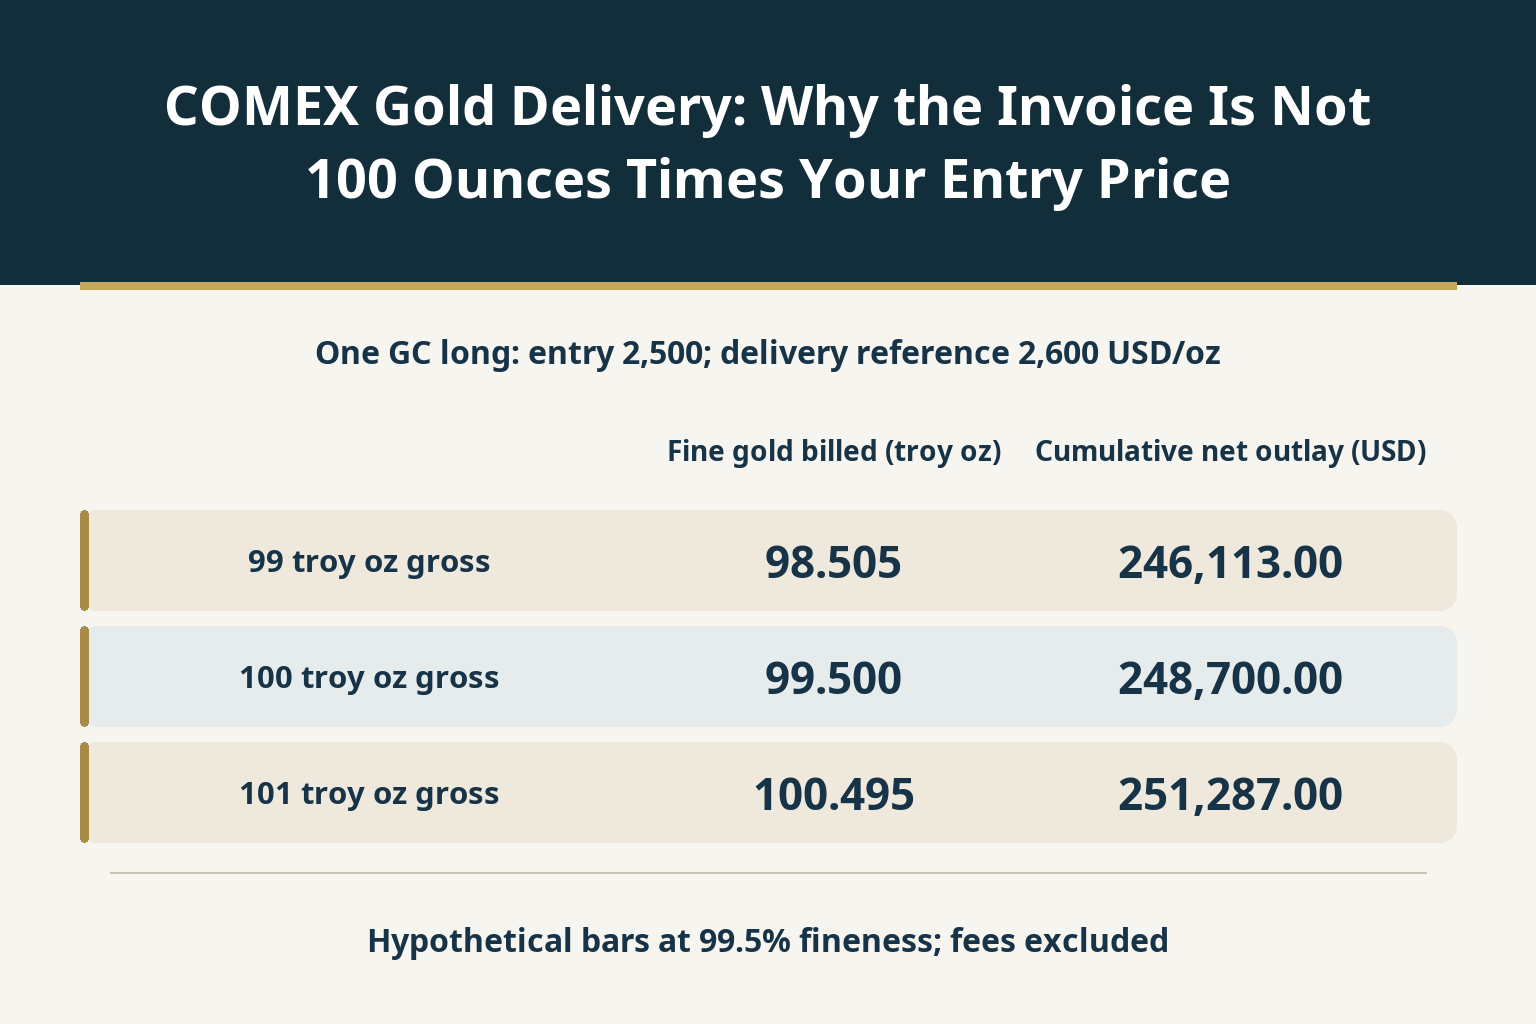
Assume one GC long entered at $2,500 per quoted ounce and a delivery reference of $2,600. Each row below represents an independent alternative bar at 99.5% fineness, with all other delivery requirements assumed satisfied. It is not a bundle of three 100-ounce bars delivered against one contract. Fees, financing, tax and storage are initially excluded.
The futures side is identical in all three cases: 100 × ($2,600 − $2,500) = $10,000. The metal side changes with fine weight. For the middle row, 100.000 × 0.995 = 99.500 fine ounces; 99.500 × $2,600 = $258,700. Subtract the already-accounted-for futures gain to obtain accumulated net outlay of $248,700.
| Gross weight (troy oz) | Fineness (%) | Fine gold billed (troy oz) | Metal invoice (USD) | Cumulative futures P/L (USD) | Cumulative net outlay (USD) |
|---|---|---|---|---|---|
| 99.000 | 99.5 | 98.505 | 256,113.00 | +10,000.00 | 246,113.00 |
| 100.000 | 99.5 | 99.500 | 258,700.00 | +10,000.00 | 248,700.00 |
| 101.000 | 99.5 | 100.495 | 261,287.00 | +10,000.00 | 251,287.00 |
The smallest dollar payment belongs to the smallest fine-gold quantity. Comparing those totals as if they bought identical assets would be a mistake. The middle row's net cost per fine ounce is $248,700 ÷ 99.500, or approximately $2,499.497487. Dividing by the nominal contract quantity of 100 would conceal the physical quantity difference rather than explain it.
When does the entry price really cancel the later price?
Write the nominal contract quantity as Q = 100. Before other costs, the combined cash ledger is C = WP − Q(P − F0) = QF0 + (W − Q)P. The first term is $250,000. The second is the delivered fine quantity's difference from the nominal futures quantity, valued at the delivery reference.
Only when W equals Q does this simplified total reduce exactly to QF0. A bar whose gross weight is 100 does not automatically satisfy that condition. In our middle case W − Q = −0.500, leaving a −$1,300 quantity adjustment at P = $2,600. For the heavier alternative, W − Q = +0.495, so the adjustment is +$1,287 instead.
This is a reconciliation identity, not a trading opportunity. The buyer receives different quantities of fine gold, must meet delivery obligations and may incur costs omitted here. If the practical question is how to size a hedge for a specific physical requirement, that is a separate exposure-matching exercise. Do not infer that every long GC position guarantees an exact purchase price for whatever bar eventually arrives.
A lower gold price can produce a higher combined outlay
Now keep the middle bar fixed at 99.500 fine ounces and retain the $2,500 entry. Change only the delivery reference, treating the rows as separate outcomes rather than a trading path. At $2,400 the metal invoice falls to $238,800, but the futures account has lost $10,000. That loss must be added to the purchase cash already paid: $238,800 − (−$10,000) = $248,800.
| Delivery reference price (USD/oz) | Metal invoice (USD) | Cumulative futures P/L (USD) | Cumulative net outlay (USD) | Net cost per fine oz (USD) |
|---|---|---|---|---|
| 2,400.00 | 238,800.00 | −10,000.00 | 248,800.00 | 2,500.502513 |
| 2,500.00 | 248,750.00 | 0.00 | 248,750.00 | 2,500.000000 |
| 2,600.00 | 258,700.00 | +10,000.00 | 248,700.00 | 2,499.497487 |
Across the $2,400 and $2,600 outcomes, the combined outlay falls by $100 as the reference price rises by $200. The sensitivity is W − Q = −0.500 ounce: the futures position covers slightly more than the fine-gold quantity received. If W were greater than 100, the sign would reverse; if it equalled 100, this price sensitivity would vanish before costs.
The table does not say falling gold prices always make delivery more expensive. It says a fixed nominal hedge and a different physical quantity do not cancel perfectly. The negative futures result is especially useful for checking spreadsheet signs: subtract a signed profit, or add an absolute loss, but never subtract the loss again as though it were a receipt.
Add storage without confusing cost with available cash
Delivery-related fees require a separate line. Under Rule 706.F, handling and storage must be paid through the delivery day, including that day. Qualifying storage prepaid beyond delivery, for a period not exceeding 30 days, is reimbursed by the buyer's clearing member to the seller's clearing member for the unexpired portion through an invoice adjustment. As an independent illustration—not a current warehouse tariff—assume $30 prepaid for a 30-day month and 12 unexpired days after delivery. The reimbursement is $30 × 12/30 = $12.
Using the middle bar at the $2,600 reference, the invoice becomes $258,712 including that item; accumulated net outlay after the $10,000 futures gain becomes $248,712. Later storage, load-out, transport, insurance, brokerage, tax and financing remain separate inputs. Do not charge the same prepaid days twice or assume this illustration covers every invoice adjustment.
Accumulated net outlay is not necessarily the amount that must arrive on delivery day. The clearing member's funding instruction concerns the invoice, while earlier gains may have been withdrawn or committed elsewhere. Initial margin is collateral, not a commodity down payment; its release can help funding only when it is actually available. Adding it permanently to acquisition cost and also treating its return as profit would confuse collateral transfers with purchase expenses and profit.
For example, if $10,000 is freely available at the funding deadline, with no other obligations or collateral release, the additional cash needed for the $258,712 invoice is $248,712. If available cash is zero, the new transfer is $258,712 instead. The acquisition ledger has not changed; the location and availability of money have. An expected margin release should not be counted in both available cash and a separate funding credit.
Delivery transfers the warrant; moving the bar out of storage is another step. Understanding warehouse warrants and physical delivery helps identify what asset has changed hands without mistaking a completed invoice for completed transportation.
A five-step check before accepting the reconciliation
- Match the contract code, month and quantity to the delivery notice. Establish that the records concern standard GC and identify any position changes.
- Match warrant number, approved brand and facility; distinguish gross weight, fineness and the fine quantity actually billed. Resolve unit or rounding differences from the documents.
- Trace the invoice reference to the applicable intention date and check the month-end exception. Reconcile the futures ledger to that same reference, including required adjustments.
- Recalculate metal amount, signed futures result and accumulated net outlay separately. Then add each documented fee once and calculate any unit cost using actual fine ounces.
- Build a dated funding schedule: invoice deadline, available cash, earlier margin movements, collateral release and any later storage or load-out payments. A correct total does not prove the cash is available on time.
The reconciliation is complete only when quantity, price basis, signed cash flows and timing all agree. If one does not, the unexplained difference belongs on an exception list—not in an assumed “100 ounces at my entry price” total.


